How to Automate Rent Roll and Operating Statement Spreading
Automation cuts rent roll processing time in half while catching errors manual workflows miss.
Spreading is the term underwriters use for taking a borrower's rent roll and operating statement and turning them into a standard format the credit team can actually analyze. Doing this by hand still describes most of the commercial real estate lending business today, and that's the gap this piece is about. AI now handles the extraction, the normalization, and a good part of the risk analysis that used to sit with a human and a set of PDFs. This isn't a forecast about where the industry is headed. It's a description of what's already running at several large lenders and asset managers, and a guide to what adopting it actually requires.
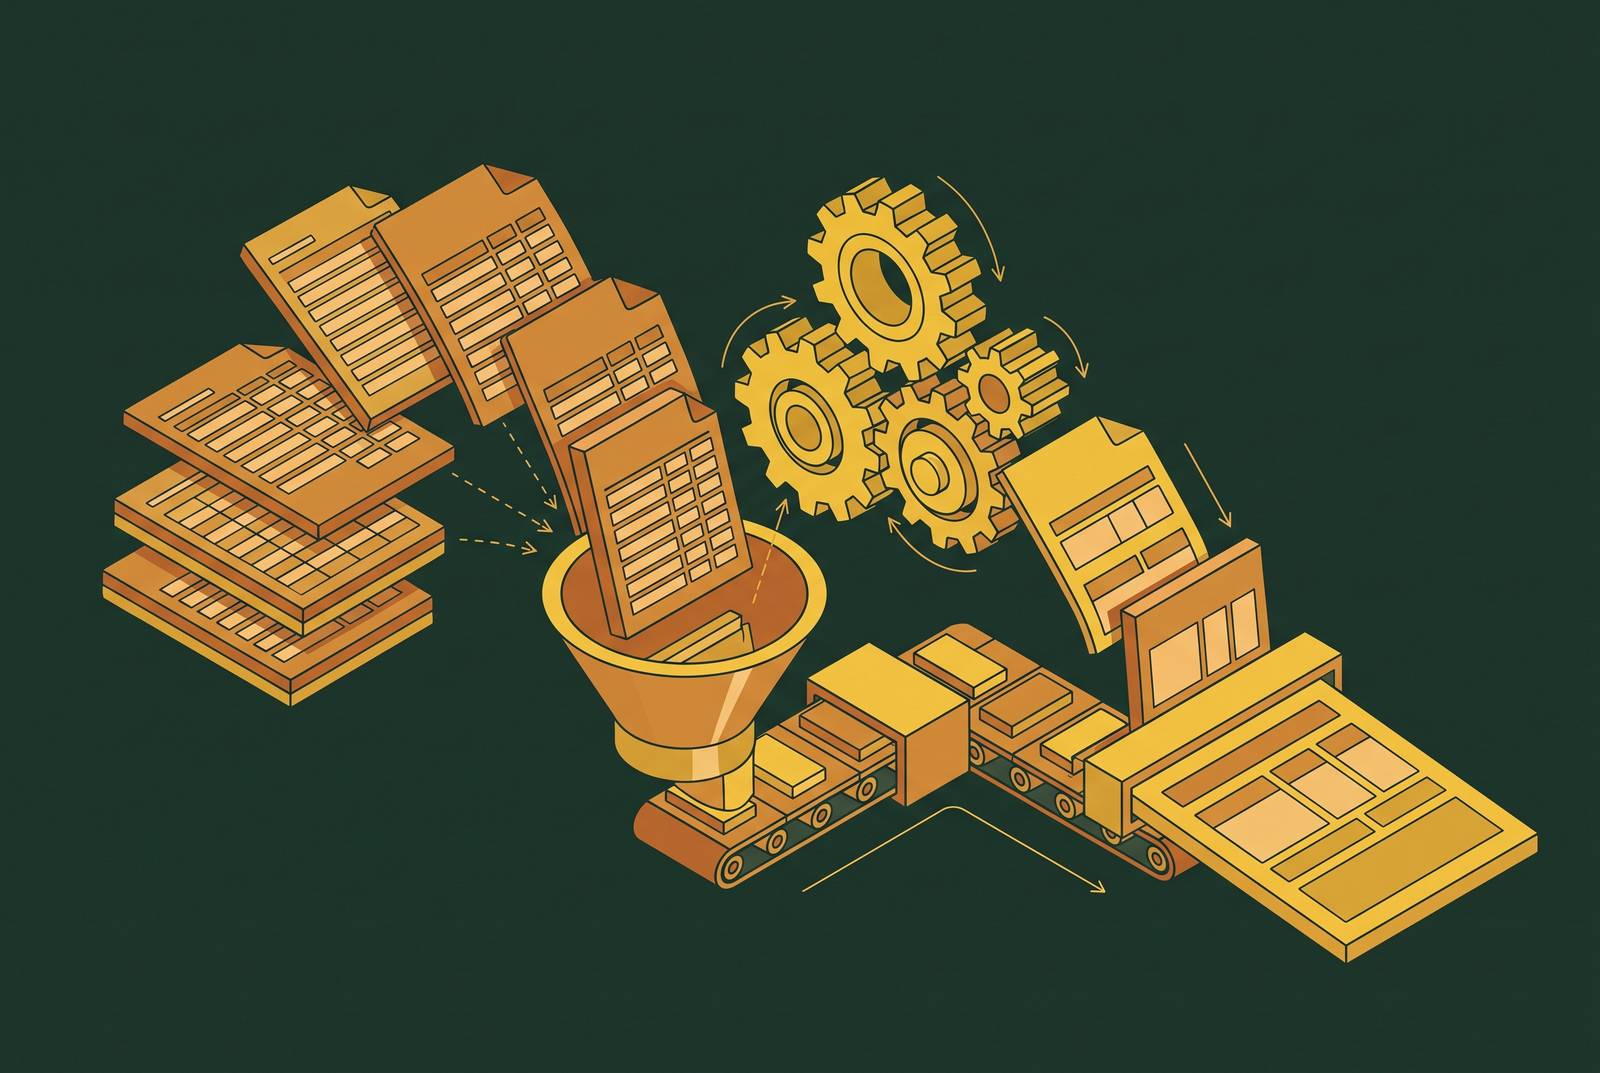
AI automates rent roll and operating statement spreading through three linked stages. At intake, optical character recognition and intelligent document processing convert scanned PDFs into machine-readable text, and models trained specifically on CRE documents classify each file by type and match it to the correct borrower entity without a person sorting the stack first. Normalization follows: the platform maps every source layout, whether it originated in Yardi, MRI, RealPage, or a manually built Excel file, onto one common schema, so base rent, square footage, lease dates, reimbursement type, and every other field mean the same thing regardless of format. Spreading then maps each revenue and expense line to a standard chart of accounts, catches non-recurring items and below-market management fees, and runs the cross-document check between gross potential rent on the rent roll and effective gross income on the T-12 that manual workflows tend to skip under time pressure; agentic platforms carry the output further still, flagging lease expiration concentrations, DSCR covenant drift, and vacancy divergence, and drafting a credit memo ready for underwriter review.
A rent roll is the per-lease record for a property: tenant name, square footage, rent rate, lease start and end dates, concessions, reimbursement structure. It's the atomic unit of income analysis for anything that produces rental income. The T-12, or trailing twelve-month operating statement, is the other half: gross income, vacancy, operating expenses, and the net operating income that falls out of those. You need both together, because the rent roll tells you who's paying and on what terms, while the T-12 tells you whether the money actually showed up. The gap between what a rent roll promises and what a T-12 confirms is where underwriting risk actually lives.
A single deal can involve several operating entities, multiple guarantors, and years of financials, arriving as a stack of documents in wildly different formats. At the scale the largest real estate asset managers operate, this stops being a workflow annoyance. The ten biggest managed a combined $1.9 trillion in assets as of 2023, and at that size, rent roll accuracy is a matter of portfolio integrity, not staff convenience.
Where manual spreading breaks down at each stage
The failure starts before anyone opens a spreadsheet. Borrowers submit one bulk PDF covering every entity, every tax year, every property, and an underwriter has to sort it by hand before a single number gets entered anywhere.
Then comes data entry, where copy-pasting numbers from a scanned image into Excel introduces keying errors that sit quietly until they affect a decision: a broken formula, a line item one row off, a version of the file that isn't the one everyone thinks they're using. Normalization is its own problem. A rent roll exported from Yardi doesn't look anything like one from MRI, and neither resembles a manually built Excel file from a smaller sponsor. Reconciling those layouts is skilled work, done almost entirely by hand, deal after deal.
Cross-document consistency tends to fail quietly too. If the occupancy figure on the rent roll contradicts the revenue line on the T-12, a rushed analyst is more likely to average the discrepancy away than to dig into why it exists. And covenant tracking rarely survives past closing: a DSCR or occupancy threshold set at origination almost never connects to whatever system would flag it once the loan is being serviced, so monitoring quietly falls off after the deal is done.
Industry research from 2024 put a number on this: lenders without integrated data systems spend an estimated 20 to 35 percent of origination team capacity on manual reconciliation work that produces no credit output at all, and that share grows as the portfolio does. Data fragmentation is widely cited as a top operational constraint for institutions carrying real estate credit exposure. Put plainly: a senior analyst might spend 20 to 30 minutes on data entry alone before deciding whether to pass on a single offering memorandum, and at 10 to 15 memos a week, that's several hours of a skilled analyst's time spent producing nothing anyone can act on.
How do lenders use AI to automate rent roll and operating statement spreading for commercial real estate underwriting?
The first thing AI needs to do is figure out what each page even is, a 1040, a 1065, a rent roll, a lease abstract, without a person sorting the stack first. Optical character recognition and intelligent document processing turn scanned images and PDFs into machine-readable text, and models trained specifically on CRE documents then classify the fields using the industry's own terms rather than generic labels borrowed from some other kind of lending.
Entity matching handles the part that trips up manual intake the most: linking each document to the right borrower entity across a deal with several subsidiaries, a joint venture, maybe an SPV layered on top. Platforms built for this, PRODA and Kolena among them, use machine learning to read varying layouts, whether that's Excel, PDF, or an export straight out of Yardi, MRI, or RealPage, without forcing the user to map every field to a fixed template each time a new format shows up. Kolena's approach lets analysts write plain-language instructions describing what to pull out of a document, and the platform applies that instruction the same way across every file it sees after that, regardless of format.
What comes out the other end is a document set that's already sorted and matched to the right entity, ready to be spread. That's the hour or two of pure sorting and identification work that used to eat into an underwriter's day before any real analysis could even start.
How AI normalizes rent roll data into a spreadable format
Two rent rolls covering comparable properties almost never share column headers, date formats, or even the same convention for expressing rent (per square foot versus monthly versus annual). Normalization means mapping every source layout onto one schema, tenant name, square footage, base rent, lease commencement and expiration, renewal options, concessions, reimbursement type, so the numbers mean the same thing no matter where they came from.
Platforms built for this pull a full set of fields across every section of a lease, and every extracted figure gets cited back to the exact page it came from, which gives an analyst a direct way to check rent, term, or occupancy detail during lender review or later in an audit. The fields that matter most for NOI projections or lease negotiation, base rent, escalation schedule, reimbursement terms, renewal options, landlord and tenant restrictions, surface automatically instead of needing someone to hunt for them line by line.
Once a rent roll sits in a common schema, comparing it against other properties, other markets, or other property management systems stops being a manual reconciliation project and becomes something closer to a query. PRODA's client results give a sense of what that looks like at scale: Blackstone cut its rent roll processing time roughly in half, and Hines captured a meaningfully larger share of standardized data across its portfolio, both the direct result of applying one schema consistently across a large and varied set of properties.
How AI spreads operating statements and surfaces NOI adjustments
Spreading a T-12 means sorting every revenue and expense line into a standard chart of accounts, calculating NOI, catching anything non-recurring, and flagging variances against prior years or market benchmarks. AI maps the wide range of accounting presentations it encounters, one property manager's QuickBooks export, another's CPA-prepared statement, into the same set of categories every time, which removes the judgment calls that made two analysts spread the same deal two different ways.
It also catches the adjustments underwriters make by hand and inconsistently: a management fee that's below market, a capital expenditure buried in operating expenses, a tenant improvement allowance that throws off the year-over-year comparison. And it runs the cross-document check that manual workflows tend to skip under time pressure, comparing gross potential rent on the rent roll against effective gross income on the T-12 and raising a flag on any gap instead of quietly averaging it away.
The multi-entity complexity that makes CRE spreading harder than ordinary financial spreading, subsidiaries, joint ventures, SPVs, gets handled by agentic platforms that consolidate everything into one spread and align line items across statements even when the accounting standards differ from entity to entity. Research published in Management Science by INFORMS in 2024 found automated underwriting produced up to 10.2 percent higher loan profits and 6.8 percent lower default rates compared to manual underwriting, largely because consistent, repeatable analysis improves which deals get selected and catches risk earlier in the process.
How risk flags and credit signals get surfaced automatically
Purpose-built platforms don't stop once the template is filled in. They flag the conditions that deserve an underwriter's attention before a person ever looks at the spread.
Lease expiration concentration is a good example: identifying that an outsized share of a rent roll's square footage rolls within the same 12 or 18-month window is a risk signal, but finding it manually means counting across dozens or hundreds of rows by hand. Vacancy and collections divergence gets caught the same way, when physical occupancy, economic occupancy, and actual rent collected start to pull apart from each other, and each kind of gap points to a different underlying issue, whether that's a credit tenant not actually paying, a gross-up clause, or concessions burning off.
Connecting the spread to the loan's actual terms lets a platform flag when DSCR or occupancy is drifting toward a covenant threshold, restoring the monitoring link that normally breaks the moment a loan closes. Agentic platforms take this a step further and draft a credit memo straight from the completed spread, laying out the risk flags, the NOI calculation, and the key lease terms in a format ready for an underwriter to review rather than one they have to build from scratch. Lenders using automated spreading consistently report meaningful time-to-decision improvements, with approval cycles compressing from weeks down to days once AI is doing the document extraction and first-pass analysis.
What the efficiency gains look like in practice
Freddie Mac's May 2025 analysis of lenders maximizing AI-enabled underwriting found up to 40 percent cost savings in loan processing, $1,500 saved per loan (a 14 percent reduction), and a production cycle five days shorter than the manual equivalent. Underwriters at institutions using these tools handle a larger volume of submissions without adding headcount, the same team simply covers more deal flow.
A 2026 industry survey from TIMVERO found institutions running purpose-built AI underwriting platforms cut analyst time per commercial loan by 40 to 60 percent. Taktile's analysis from April 2026 put manual spreading work reduction at up to 80 percent for credit teams using agentic AI. On accuracy, Purpose-built spreading platforms report high accuracy scores on completed spreads, a bar manual spreading, subject to fatigue and inconsistency across analysts and deals, doesn't reliably clear.
CAERUS Debt Investments reports saving roughly one to two hours per rent roll using PRODA, which lets the firm respond to opportunities while the data is ready for analysis before competitors have even finished sorting their documents. The MBA projects commercial mortgage origination will hit $806 billion in 2026, up from $633.7 billion in 2025. Teams that can process more volume per analyst are the ones positioned to take a bigger share of that growth without needing to hire proportionally.
Where the CRE lending market creates urgency for adopting this now
MBA data shows total CRE lending reached $498 billion in 2024, up 16 percent year-over-year, with fourth-quarter originations alone surging 84 percent year-over-year. That's a pace that strains manual workflows even before factoring in where 2026 volume is projected to land.
Margins are tightening at the same time volume is climbing. Average commercial mortgage spreads compressed significantly in the fourth quarter of 2024, and when pricing power shrinks, operational efficiency becomes the lever that's still available to pull. More deal flow also means more submissions competing for the same lender's attention, which rewards whoever can turn analysis around fastest, not just whoever offers the sharpest rate.
Data infrastructure quality has emerged as a defining strategic differentiator for CRE firms going forward, and the gap between firms running a unified data layer and firms still reconciling spreadsheets by hand widens with every deal cycle that passes. A 2023 survey found only about one in three CRE firms were using lease abstraction or document intelligence software at all, meaning most of the market is still doing this work manually. That's the window: the firms that automate now get the advantage before it becomes the baseline everyone's expected to meet.
How to evaluate platforms built for CRE spreading versus generic alternatives
A general-purpose document AI, trained on broad datasets pulled from all kinds of industries, won't reliably know what to do with a DSCR calculation or an NNN reimbursement structure, and it won't reliably tell the difference between effective and potential gross income without training built specifically around CRE documents. That distinction should shape how a platform gets evaluated, not just whether it works.
Coverage of document types matters first: does the platform handle rent rolls, T-12s, lease abstracts, tax returns across entity types, and appraisals, or only a slice of that stack that leaves gaps someone still has to fill by hand? Source citation matters just as much. Every figure a platform extracts should trace back to the exact page it came from, because lender review and audit both demand outputs that can be defended, not a black box that just spits out a number.
Schema flexibility is worth checking closely too. A platform that forces every document into one fixed, proprietary template creates ongoing maintenance work every time a borrower's format changes, whereas a platform that interprets schema through machine learning adapts to format variation without anyone remapping fields by hand. Direct integration with Yardi, MRI, and RealPage is worth asking about specifically, since it removes the PDF-export step that reintroduces exactly the formatting inconsistency the platform is supposed to solve.
Then there's the question of how far the platform actually goes: does it stop at extraction, or does it carry through to spreading, flagging, and a draft memo, the difference between a data tool and something that actually changes the workflow. And enterprise security isn't optional given what's in these documents. Rent rolls and operating statements carry sensitive tenant and borrower information, so SOC 2 compliance, data residency controls, and role-based access aren't features that differentiate a good platform from a great one; they're the entry price.
How to implement automated spreading as a workflow change, not just a software purchase
The most common way this fails has nothing to do with the software itself. A team buys a spreading tool, runs it alongside the existing Excel process "just to verify," and never actually finishes the switch. The tool ends up as one more step bolted onto the old workflow instead of replacing it.
Start by auditing how documents actually arrive today, email, a lender portal, a shared drive, and map out how they get sorted and named and who's doing that sorting. That step alone usually reveals where AI classification produces the first real time savings, often before a single dollar figure gets touched.
Before picking a platform, decide what the standard output schema should look like: which line items matter, what flags are non-negotiable, what the credit memo format needs to include. Those decisions should come first, because otherwise whatever defaults the platform ships with quietly become the firm's own standard, by inertia rather than intention. And when it's time to pilot, pick a document type with clear volume and a clear pain point, rent roll normalization across a portfolio review is a far better place to start than a tangled multi-entity tax return spread, where the complexity can obscure whether the tool is actually working or just adding a new layer of confusion.