NNN vs. Gross Lease Underwriting Differences for CRE Lenders
Modified gross leases hide the mispricing risks that NNN and full-service structures expose.
Lease structure determines how CRE lenders calculate net operating income, and getting that calculation wrong is the single most common way a loan gets mispriced. NNN and gross leases split expenses differently, and that split creates two distinct underwriting environments with different risk drivers, different DSCR behavior, and different documentation demands. Most underwriters treat modified gross leases as a footnote between the two clean categories, something to skim past on the way to the numbers that matter. That instinct undersells the category: the footnote is where the mispricing actually happens, and it deserves more scrutiny than either clean category gets.
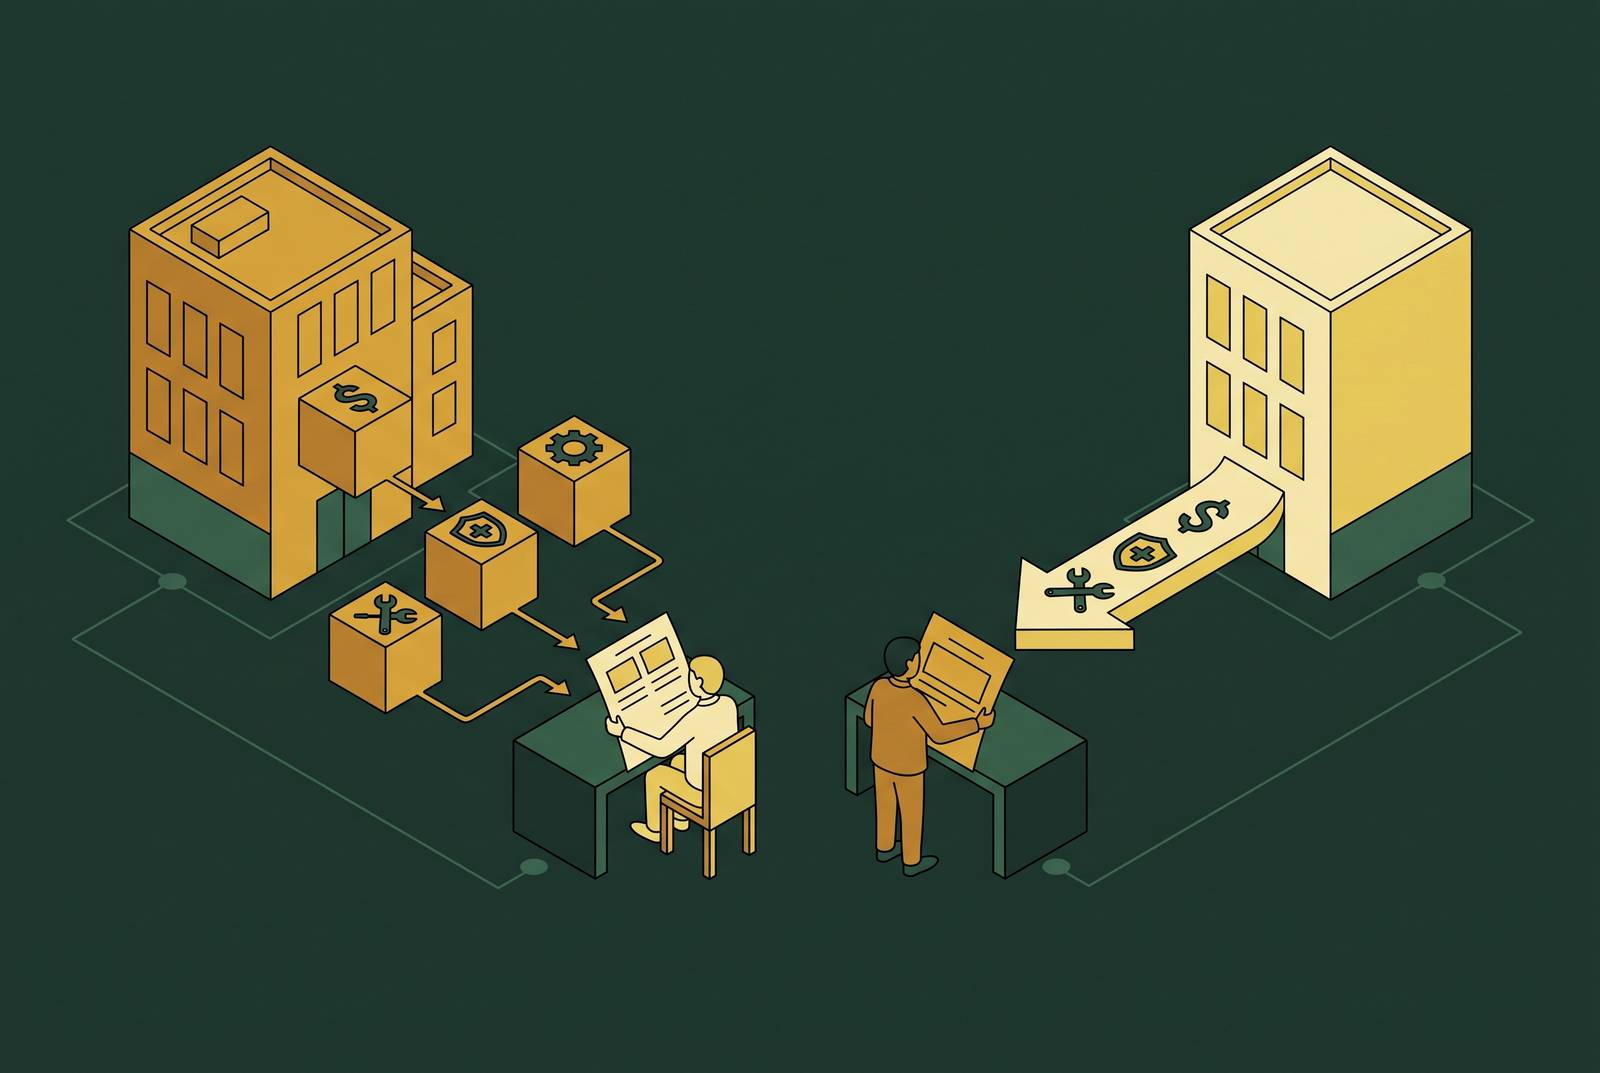
Who pays for what is where the split starts. In a triple net (NNN) lease, the tenant covers property taxes, insurance, and common area maintenance on top of base rent, so the landlord's NOI stays largely insulated from operating cost swings. In a full-service gross (FSG) lease, the landlord charges a higher base rent meant to cover those same costs, and keeps the exposure sitting on its own books. When that built-in buffer is sized right, the lease is clean. When it isn't, the buffer erodes and NOI erodes with it.
Between those two poles sits the category lenders can't afford to wave through: modified gross leases, base year clauses, and expense stops. A base year clause ties the tenant's expense recovery to actual operating costs in a specified year, usually the year the lease starts. That sounds harmless until the base year goes stale. A 2018 base year measured against 2026 operating expenses quietly shifts years of inflation back onto the landlord, and none of it shows up on the face of the rent roll. Renewals reset that floor too, so a lease renewal can compress NOI for the new term the moment it's signed. A "gross lease" with a current, tight expense stop behaves very differently from one sitting on a stale pre-pandemic base year, even though both get filed under the same generic label on a rent roll summary. Reading past that label is the job, not an optional extra step.
Asset class matters here too. NNN dominates single-tenant retail, industrial, and most newer multi-tenant product built in the last decade or so. FSG persists mainly in Class A office and older multi-tenant buildings, where tenants still have enough leverage to make the landlord absorb operating risk.
What operating expense inflation is doing to gross lease NOI right now
Insurance is the sharpest pressure point on the expense side. Commercial property insurance costs for multifamily buildings rose more than 75% in real terms between 2019 and 2024, climbing from $39 to $68 per unit per month. That climb didn't level off in 2024 either: property insurance costs rose 17.4% that year alone. Property taxes and utility costs are stacking on top of that, and rising electricity demand is pushing utility costs higher across a range of markets.
CBRE traced the transmission mechanism and found that roughly 95% of operating expense movement follows lagged CPI, with a 1% move in CPI flowing through to about a 1.3% move in OpEx roughly 12 months later. Running that math against CPI readings of 2.7% to 3.5% in 2024 and 2025 points to OpEx growth of 3.5% to 4.5% heading into 2026 — a figure worth sitting with, because it means a model built on last year's expense line is already out of date before anyone's touched it.
For FSG buildings, the landlord eats all of that, with nowhere to pass it along. In an environment where cumulative OpEx inflation reaches 33%, FSG-heavy buildings show NOI compression of 8% to 12% against original underwriting, absent any renegotiation of rent. A model built 18 to 24 months ago is very likely overstating both current and forward NOI. Anyone re-underwriting an acquisition or refinance on gross lease product should start from that assumption rather than treat it as a remote risk to footnote. Historical actuals can't be taken at face value without stress-testing the expense line against where CPI is actually heading.
NNN assets aren't immune to inflation, but the mechanism is different. Instead of hitting the landlord's operating cost line directly, the pressure shows up later, in lease renewal negotiations and in tenant credit stress, as tenants absorb costs that eventually strain their own margins.
How lease structure flows into NOI calculation and why lender-constructed pro formas diverge from borrower submissions
Standard practice among CRE lenders is to build an independent pro forma rather than accept the borrower's numbers as given. The rent roll and the sponsor's pro forma are inputs to that process. A lender who treats them as conclusions to sign off on is pricing blind.
On NNN rent rolls, the adjustments cluster around a few things. Vacancy and credit loss factors matter most as leases approach expiration and rollover risk rises. A tenant-by-tenant recovery analysis has to check the recovery structure, whether it's full NNN, base year stop, or modified gross, the base year value on each lease, and how occupancy trends affect the recovery pool going forward. Replacement reserves matter too, for structural items an NNN lease often doesn't fully cover, like roof and HVAC on older buildings. Double-net leases in particular still leave the landlord holding real maintenance risk that a quick read of "NNN" on the rent roll can mask entirely.
On gross lease rent rolls, the work shifts to the expense side. The lender has to forecast operating expense growth against fixed rents, because the FSG rent figure is gross revenue rather than net income; modeling the expense line independently is the whole job. That means testing whether the premium baked into gross rents actually covers forward OpEx, or whether the leases are already underwater on a net basis and nobody's noticed yet. It also means checking every base year term on every modified gross lease in the roll for staleness, lease by lease.
The valuation stakes here are not small. At a 6% cap rate, $27,000 in additional annual NOI translates into $450,000 of property value on the exact same physical building. A lender and a borrower running different OpEx assumptions can land on materially different collateral values before either side has made an actual error; they've just made different assumptions about a number nobody bothered to pin down. On a 200,000-square-foot Class A office asset in the Boston CBD, the spread between an FSG-based and NNN-based underwriting approach capitalizes to something like a $21 million valuation delta at a 7% cap rate, a gap large enough on its own to decide whether a loan clears its LTV threshold.
DSCR and debt yield behavior under each lease structure
NNN's expense pass-through cuts the odds that an unexpected cost spike compresses debt service coverage. Coverage ratios stay predictable year over year, provided tenant credit and lease duration hold up. That's the whole appeal of the structure from a lender's chair.
Gross lease debt yield is a different animal, and a harder one to hold still. The lender has to track revenue performance and expense management at the same time, because DSCR is a moving target when OpEx keeps rising against a fixed rent. Under current inflation conditions, that problem compounds: a property that cleared its DSCR test at origination can drift toward the loan covenant within the term if operating costs run ahead of what was underwritten. Lenders looking at gross lease assets now need to stress-test coverage against projected OpEx growth of 3.5% to 4.5% into 2026, not against historical averages that no longer describe the environment they're lending into.
NNN debt yield stability rests on two things lenders have to assess separately: tenant credit quality and remaining lease term. A long-duration NNN lease backed by a strong-credit tenant produces stable, predictable debt yield. A short-duration lease, or one backed by a franchisee rather than a corporate guarantee, brings rollover and re-tenanting risk that can disrupt debt yield just as abruptly as OpEx inflation disrupts a gross lease, only through a different channel entirely.
Co-tenancy clauses deserve their own line of scrutiny in multi-tenant NNN retail. If an anchor tenant leaves and triggers a co-tenancy provision, other tenants in the center can terminate their leases or demand reduced rent, and that cascade is genuinely hard to model in advance. Income can decline sharply in a scenario that wasn't visible anywhere in the rent roll at origination. The practical response from lenders: gross lease assets typically get a larger haircut to underwritten NOI and a more conservative DSCR floor, while NNN assets can price tighter but demand tougher tenant credit and co-tenancy review before closing.
Single-tenant NNN underwriting: when the lease structure shifts credit risk to the center of the analysis
Single-tenant net lease (STNL) underwriting is best understood through a bond analogy. An investment-grade tenant on a long-duration NNN lease prices like a long-duration corporate bond wrapped in a real estate hedge, and the underwriting work is as much credit analysis as it is property analysis. Treating STNL as a real estate deal first and a credit deal second gets the order backwards, and that's the mistake to fix before anything else here matters.
Cap rates move directly with tenant credit. McDonald's ground leases traded around 4.40% in the first quarter of 2026; Chick-fil-A around 4.50%. Trophy-tier tenants with 15 or more years remaining on their leases cluster in the 4.40% to 5.30% range. Against that, Marcus & Millichap's 2025 report put the mean STNL cap rate at 6.5%, a 12-year high, which shows just how far the broader market has repriced outside that top credit tier.
The spread between NNN property yields and the bond yields of the same tenant is a structural feature of the asset class, not a pricing anomaly. Dollar General NNN properties yield around 7.15%, a spread of roughly 185 basis points over comparable bonds. CVS NNN properties yield around 6.80% against CVS bonds around 5.10%, a 170 basis point spread. That gap compensates for illiquidity and for a risk the bond simply doesn't carry: dark-store risk. The day a tenant closes a location, the property's value can drop hard, because the cap rate was mostly a function of the tenant's balance sheet, not the real estate's underlying use value. A Dollar General in a tertiary market with 12 years left on the lease is worth a fraction of its going-concern value the moment the store goes dark, and no amount of remaining term fixes that.
Non-rated and franchisee-backed NNN leases need their own underwriting lens entirely. The brand on the sign is a separate question from the credit behind the rent, and lenders have to separate corporate-guarantee leases from franchisee-guarantee leases before pricing risk, not after signing.
The market has bifurcated further into 2026. Premium credit assets with long remaining terms compressed even more, with single-tenant NNN cap rates edging to 6.80% overall in the first quarter of 2026 and rising slightly to 6.82% by the second quarter; retail alone sat at 6.55% in Q1, rising to 6.60% in Q2. Shorter-term and non-rated assets drifted wider over the same stretch, and the gap between the two tiers has widened enough to demand genuinely separate lending strategies for each bucket. Lenders compete hard to finance investment-grade STNL assets, which shows up in better rates and terms than comparable retail product, and that competition is itself a signal of how much clarity a strong credit tenant buys an underwriter. Sponsors should treat tenant credit documentation as a first deliverable for that reason, not something assembled after the term sheet is already on the table.
How lease structure shapes loan terms, lender appetite, and the documentation lenders need at each stage
NNN's financing advantage comes from cleaner NOI, more predictable DSCR, and less uncertainty for the lender. That combination usually buys tighter pricing, higher leverage, and a wider field of lenders competing for the deal. Many lenders actively target investment-grade STNL credit for exactly this reason.
Gross lease loans get structured more conservatively as a matter of course, and that reflects the correct instinct rather than excess caution. Lenders lean on more conservative underwriting assumptions, sometimes require larger operating expense reserves or escrow accounts, and price a wider margin to account for NOI that can move more than the rent roll suggests. The loan terms are, in effect, a direct readout of how much uncertainty sits in the expense line.
What a lender needs from a sponsor differs by lease type, and getting the documentation right the first time saves both sides real underwriting time. On NNN deals, that means full lease abstracts with the recovery structure identified per tenant (full NNN, modified gross, or base year stop), tenant credit documentation distinguishing corporate guarantees from franchisee guarantees, co-tenancy clause language reviewed and disclosed, and a rent roll annotated with expiration dates and renewal option terms. On gross lease deals, it means historical operating expense actuals, not just rent roll revenue, so the lender can check whether the built-in rent premium has actually kept pace with real costs; base year identification on every modified gross or expense stop lease, with a clear read on whether that base year is current or stale; and forward OpEx projections backed by actual insurance and property tax documentation, rather than an assumed growth rate pulled from a template.
The recovery analysis on a multi-tenant NNN rent roll is a matrix problem: expenses, tenants, and years, all cross-referenced against each other. That's exactly where spreadsheet-based underwriting breaks down, since a single lease amendment can cascade through dozens of linked worksheets and errors compound quietly across them until someone finally notices at closing. Purpose-built CRE underwriting software can handle that cross-referencing automatically and flag base year staleness or recovery mismatches that a manual model is likely to miss, though the tool only closes the gap that careful reading was supposed to close in the first place.
The volume moving through this pipeline makes that precision non-negotiable. Net lease investment volume hit $52.4 billion for the year ending in the first quarter of 2026, up 8% year-over-year, and the second quarter of 2026 alone generated $12.8 billion, a 13% year-over-year increase according to CBRE. Lenders and sponsors are working through a high volume of these deals in a compressed window, and there isn't room left in that pace for a spreadsheet to quietly drop a base year adjustment.
The well-underwritten deal, in the end, is the one where the lender's NOI and the sponsor's NOI land in the same place, arrived at because the lease structure got read correctly from the start and the documentation left no ambiguity in the expense and recovery picture.