AI Lender Matching Platforms for Middle-Market CRE Sponsors
These platforms reduce wasted outreach by screening deals against lender criteria first.
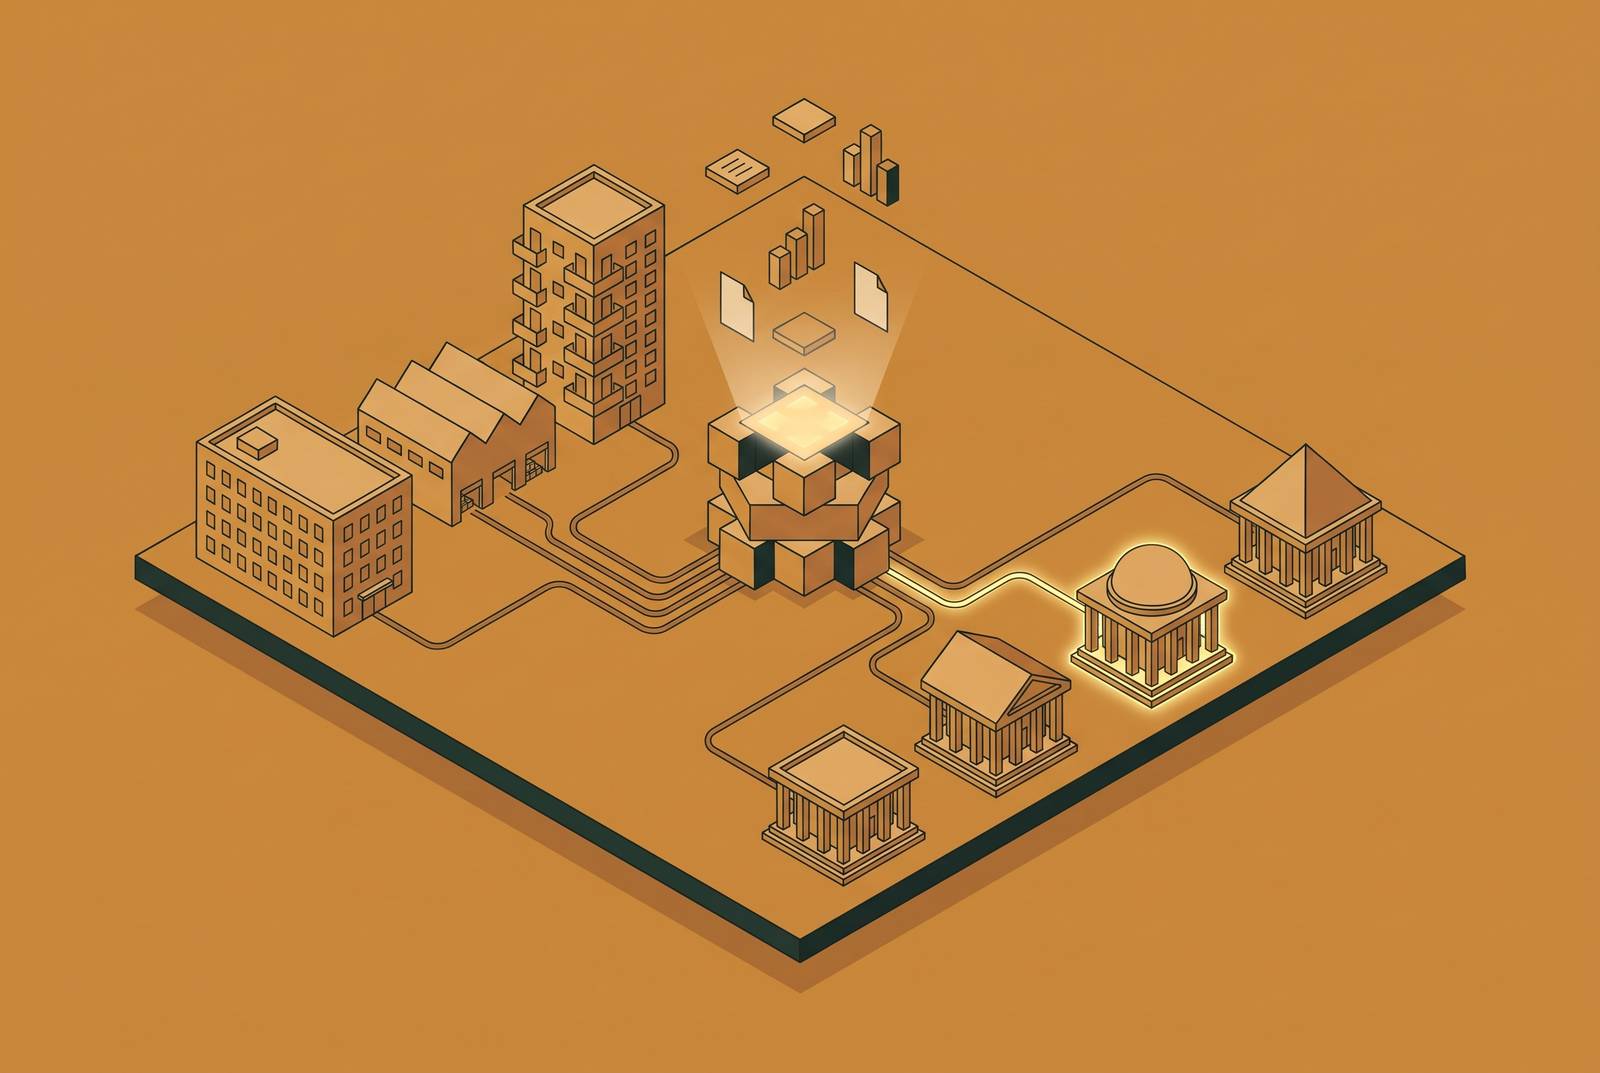
AI lender matching platforms address a structural financing gap for middle-market CRE sponsors. Their value is not broader distribution but precise alignment between a deal and a lender’s current criteria before outreach begins. That advantage depends on more than matching software. Closing a loan with a well-matched lender takes accurate preparation, program-level screening and people who carry the deal through.
Why middle-market CRE sponsors face a structural capital access problem, not just a slow market
Middle-market sponsors control most institutionally sponsored real estate, but large institutional lenders and retail channels both struggle to serve them well. These sponsors have meaningful portfolios without the dry powder that attracts the largest institutions. Their assets sit between established distribution channels. Large institutions struggle to put capital to work efficiently when the amount per asset falls below certain thresholds, so smaller assets turn to retail channels, family offices and regional insurers. The resulting financing gap exists independently of the credit cycle.
Commercial and multifamily origination volumes have risen sharply year-over-year, but deployment remains selective on asset quality, sponsorship strength and structural clarity. Those are precisely the characteristics that distinguish middle-market sponsors from one another. Sponsors approaching maturities or acquisitions therefore face a signaling problem as well as a funding problem. Reaching an unsuitable lender consumes time without establishing whether an appropriate source of capital is available.
The timing pressure begins before a transaction is secured. Platte Canyon CEO Brennen Degner said, “You need to know who the partner is going to be before or during the bid process. Deals are tough to get done when you expect to find the equity afterwards.” Debt and equity partners must be identified within that compressed window. Sequential outreach leaves little room to recover from a poor initial fit.
Why the traditional brokerage model fails exactly the sponsors who need it most
The traditional placement process depends on relationships and work done by hand, while the sponsor’s timetable calls for early, precise screening. Commercial mortgage brokerage evolved differently from residential origination, where automated underwriting and AI workflow tools are now common. The lenders it covers come from relationships built over time rather than a map of credit criteria that is kept up to date. This is a process constraint.
A broker with strong multifamily relationships may have less coverage in bridge lending, just as regional expertise may not include current criteria elsewhere. Without pre-submission screening, a file can reach a lender with the wrong geographic mandate, an incompatible LTV limit or a paused allocation to the asset class. The mismatch becomes visible during lender review, on the lender’s timetable. A declined file must be re-underwritten elsewhere, restarting the clock and damaging goodwill. Borrowers also rarely see a complete account of who received the deal, who declined and why.
Fragmented lending markets make that coverage problem harder. Bridge finance has dozens of non-bank lenders, each with its own limits on asset class, geography, construction exposure and exit strategy. A roster kept up to date by hand has trouble capturing all those differences. Middle-market sponsors need that precision because a relationship alone does not establish whether a particular program can finance a particular business plan.
What AI lender matching actually does — and the spectrum from filtered directories to program-level matching
AI lender matching checks a deal’s characteristics against lender criteria to find the lenders most likely to fit. Inputs include property type, loan amount, LTV, DSCR, geography, business plan, timeline and borrower profile. The workflow moves from intake and structuring to criteria matching, then to ranked output explaining strong and borderline fits. Hard mismatches are removed before lender review. The depth and currency of the criteria database determine how useful that screening becomes.
The lowest tier consists of keyword-filtered databases. A sponsor enters a loan type and property type, then receives lenders associated with those fields. Scoring-based matching goes further by weighting several parameters and ranking the results, but a static scoring system does not necessarily reflect what lenders are actively funding. Its apparent precision can exceed the freshness of its inputs.
Program-level matching tests the deal against specific lending programs. Each program has its own minimum DSCR and maximum LTV, along with preferences for geography, an asset appetite and a loan-size range. A lender’s general interest in an asset class does not establish eligibility for its individual programs. Closed-loop learning adds another layer by feeding term-sheet and closing outcomes back into the model, allowing matching accuracy to improve with execution data.
Pre-submission screening is therefore fundamentally different from a post-submission marketplace. The former removes incompatible programs before outreach, while the latter exposes a file to listed lenders and leaves the sponsor to sort responses. Traditional brokerage also matches before submission, using relationships and memory. Current, actively maintained criteria are more useful than a larger inventory containing institutions with no appetite for the transaction.
That distinction becomes especially valuable in fragmented segments. Bridge matching must consider LTV, LTC, construction budget as a percentage of the loan, exit strategy and sponsor track record. DSCR lending requires similarly specific treatment of property subtypes. Short-term rental properties, 5–20 unit buildings and mixed-use assets can face different thresholds depending on the lender. Current program criteria prevent a submission from relying on a threshold that has moved.
The platforms doing AI lender matching in 2026 and what distinguishes each
The platforms on offer range from AI-native brokerage and self-serve matching to advisor-paired execution and tools for research or marketplace use. Their differences extend beyond the quality of a shortlist. They can be compared by how they handle program-level screening and bankability assessment, who takes responsibility through closing and how they disclose fees. Capabilities left unestablished by a platform’s description remain unconfirmed.
YieldStack represents the AI-native brokerage model. It matches against more than 20,000 loan programs using hard program criteria and runs a bankability pre-screen before lenders see the file. A human deal team checks the proposed matches and approves which lenders to contact. The team then manages lender communication, term-sheet comparison, negotiation and closing support. Its stated proposition includes no upfront broker fees, although that alone does not establish the complete closing-fee structure.
CommLoan’s CUPID engine serves brokers seeking self-serve matching. It reads lender credit boxes in real time and accepts either an offering memorandum or manually entered deal details, returning the top three matches in under a minute. Execution remains with the broker after that output. Its distinction is current-criteria matching rather than managed placement, and the described offering does not establish a separate bankability pre-screen or fee schedule.
Gumption combines software matching with capital-markets advisors who help structure, negotiate and close transactions. Submission and term sheets are free, with a borrower origination fee applying only when a recommended lender’s loan closes. Its execution role is therefore explicit, as is the fee trigger. It suits sponsors who want an advisor’s help without a traditional retained brokerage arrangement.
CREaiD helps professionals research and find lenders, compare terms and find capital for complex deals. It is not positioned as a managed brokerage. Finance Lobby uses post-submission matching, where deals are posted for lenders to answer. Sponsors who use that model sort the responses themselves. Neither description establishes program-level bankability screening, managed execution through closing or a complete fee schedule.
How document preparation and AI underwriting connect to matching quality
Even with a lender that fits, a submission still needs to be complete. Document-to-model ingestion remains the highest-cost manual process for most CRE lending shops, requiring information from offering memoranda, rent rolls and T12s to be transferred into underwriting models. AI reduces that work on both sides of the transaction. For sponsors without large analyst teams, preparation speed directly affects how soon a matched opportunity becomes a presentable loan request.
Lender-side automation also changes what moves efficiently through a credit queue. As underwriters process more files, clean and structured submissions have an advantage over packages requiring the credit team to reconstruct missing information. Software now does some of the work that people once did by hand in intake, document intelligence, matching, underwriting and portfolio monitoring. Credit decisions still remain with the lender. Automation does not transfer that responsibility to the matching platform or the sponsor’s preparation tools.
Sponsor-side document intelligence extracts information from offering memoranda, rent rolls, T12s and property management exports into structured models. Agentic workflows extend that process by pulling data, running risk models, flagging anomalies and routing exceptions to humans without manual handoffs at every stage. Professional packages consequently require fewer analyst hours. Those packages can have an executive summary, a T12 narrative, rent roll commentary, a market overview and a sponsor bio. Preparation quality feeds directly into the accuracy of the parameters used for matching.
Transparent sourcing remains important as these workflows expand. The Federal Deposit Insurance Corporation, the Office of the Comptroller of the Currency and the Board of Governors of the Federal Reserve System issued revised model risk management guidance on April 17, 2026. Sponsors providing traceable sources and clear methodology are better positioned with lenders managing AI model risk than those submitting opaque or unverifiable outputs.
The lending backdrop in late 2026 and why matching precision matters more, not less, in an active market
A more active lending market increases the volume competing for selective deployment. The Federal Reserve’s July 2026 Senior Loan Officer Opinion Survey, released August 3, 2026, reported that moderate and modest net shares of banks eased standards for nonfarm nonresidential and multifamily loans, respectively, in the second quarter. Standards for construction and land development stayed much the same. Easing was therefore uneven across lending categories. Greater aggregate availability did not make every credit box more permissive.
FRED data for late September 2026 showed SOFR, the 10-year Treasury, the bank prime loan rate and the federal funds target range at elevated levels. The committee that sets the central bank’s rates raised them by a quarter point on September 16, 2026. Those benchmarks describe the financing backdrop. The matching question remains whether a lender’s current program fits the transaction’s economics and structure.
Execution certainty becomes more valuable in that environment. Sponsors prioritize lenders that decide quickly, take commercial views on issues and avoid unnecessary process over theoretically perfect financing that may not execute. A clean file aligned with the right credit box is better positioned to move through a busy queue than a generic broadcast. Lender-side automation reinforces that advantage by increasing file throughput while leaving selective credit decisions intact.
How sponsors should evaluate and adopt AI matching tools, and where execution gaps most often occur
For sponsors selecting a platform, the lesson is to evaluate the placement workflow rather than the AI label. Program-level screening is the threshold criterion, followed by whether the platform identifies DSCR issues, LTV problems and market gaps before submission. Database freshness deserves equally close attention. A snapshot taken from time to time may miss paused programs or changes to credit boxes, while a headline program count says little about how many can fund the deal. The evaluation should also establish whether returned terms can be compared side by side.
Execution responsibility must be clear before adoption. Sponsors should confirm who handles lender communication after matching and who stays on the file through closing. Fee transparency belongs in the same assessment. A free submission, no upfront fee and a closing-triggered origination fee describe different arrangements. The appropriate model depends on how much placement work the sponsor wants handled.
The strongest objection to AI matching concerns implementation: poor data, unclear workflow integration and excessive reliance on unvalidated output can undermine otherwise useful tools. Sponsors should check figures pulled from source documents against those documents before using the figures in a credit decision. Human validation remains part of the operating model. Platforms that connect match recommendations to actual term sheets and closings can improve over time, rather than preserve the assumptions of an initial scoring model.
CRE adoption remains early but is accelerating, with a wide gap between pilots and enterprise deployment. Sponsors moving preparation, underwriting inputs and matching into an embedded workflow can gain an advantage while that gap remains open. Unified data, AI agents and workflow tools support this progression more reliably than disconnected applications because information remains consistent and current between stages. Cleaner inputs lead to better matches, which mean fewer declined files and help keep lender relationships strong for future deals. The durable advantage is that compounding workflow.