Mezzanine Debt in Commercial Real Estate Capital Stacks
Mezzanine debt requires mastery of intercreditor agreements to survive a workout.
Mezzanine debt gets misunderstood more than any other layer in the commercial real estate capital stack, and the sponsors who pay for that misunderstanding usually find out at the worst possible time: during a workout, staring at an intercreditor agreement nobody read closely enough before signing. It sits between senior debt and equity, priced higher than a bank loan and enforced through an entirely different legal mechanism, and treating it as just "expensive debt" rather than a distinct instrument is the mistake that turns a bridge loan gap into a lost deal. Knowing how it works, and where it can break, is what lets a sponsor structure something that survives to closing instead of unwinding at the intercreditor stage.
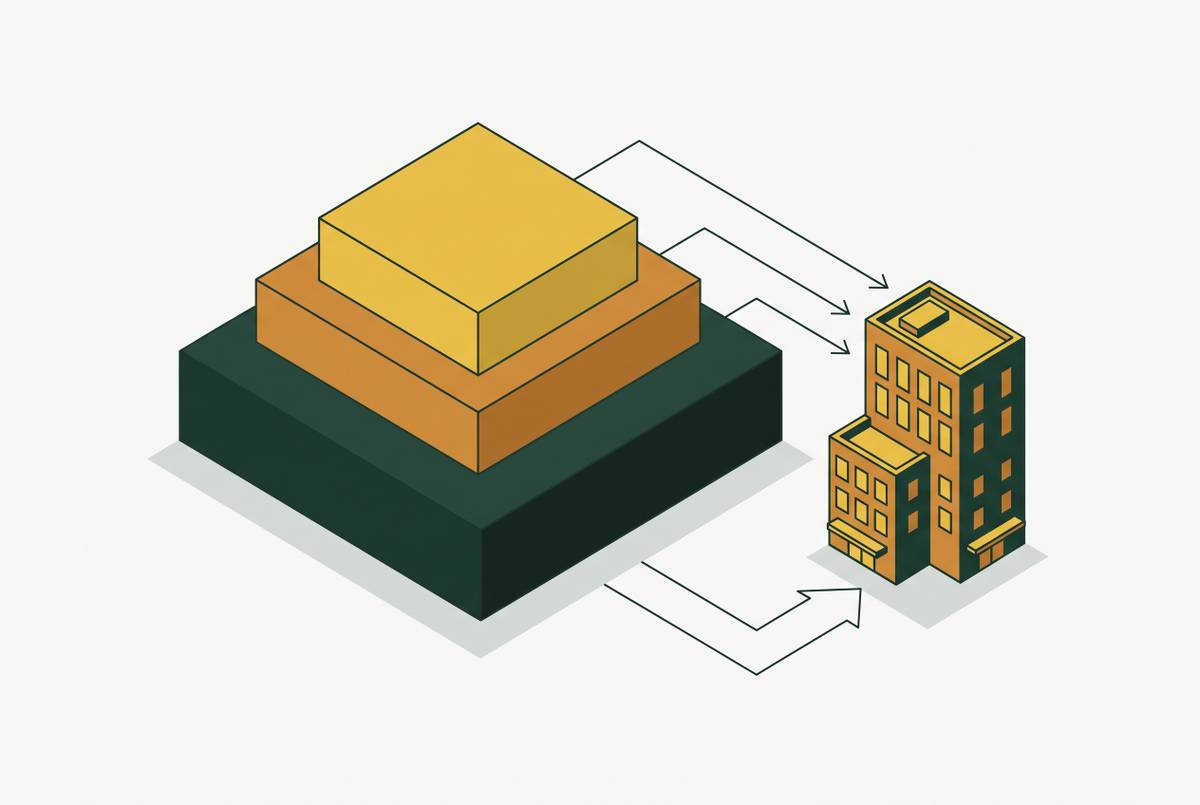
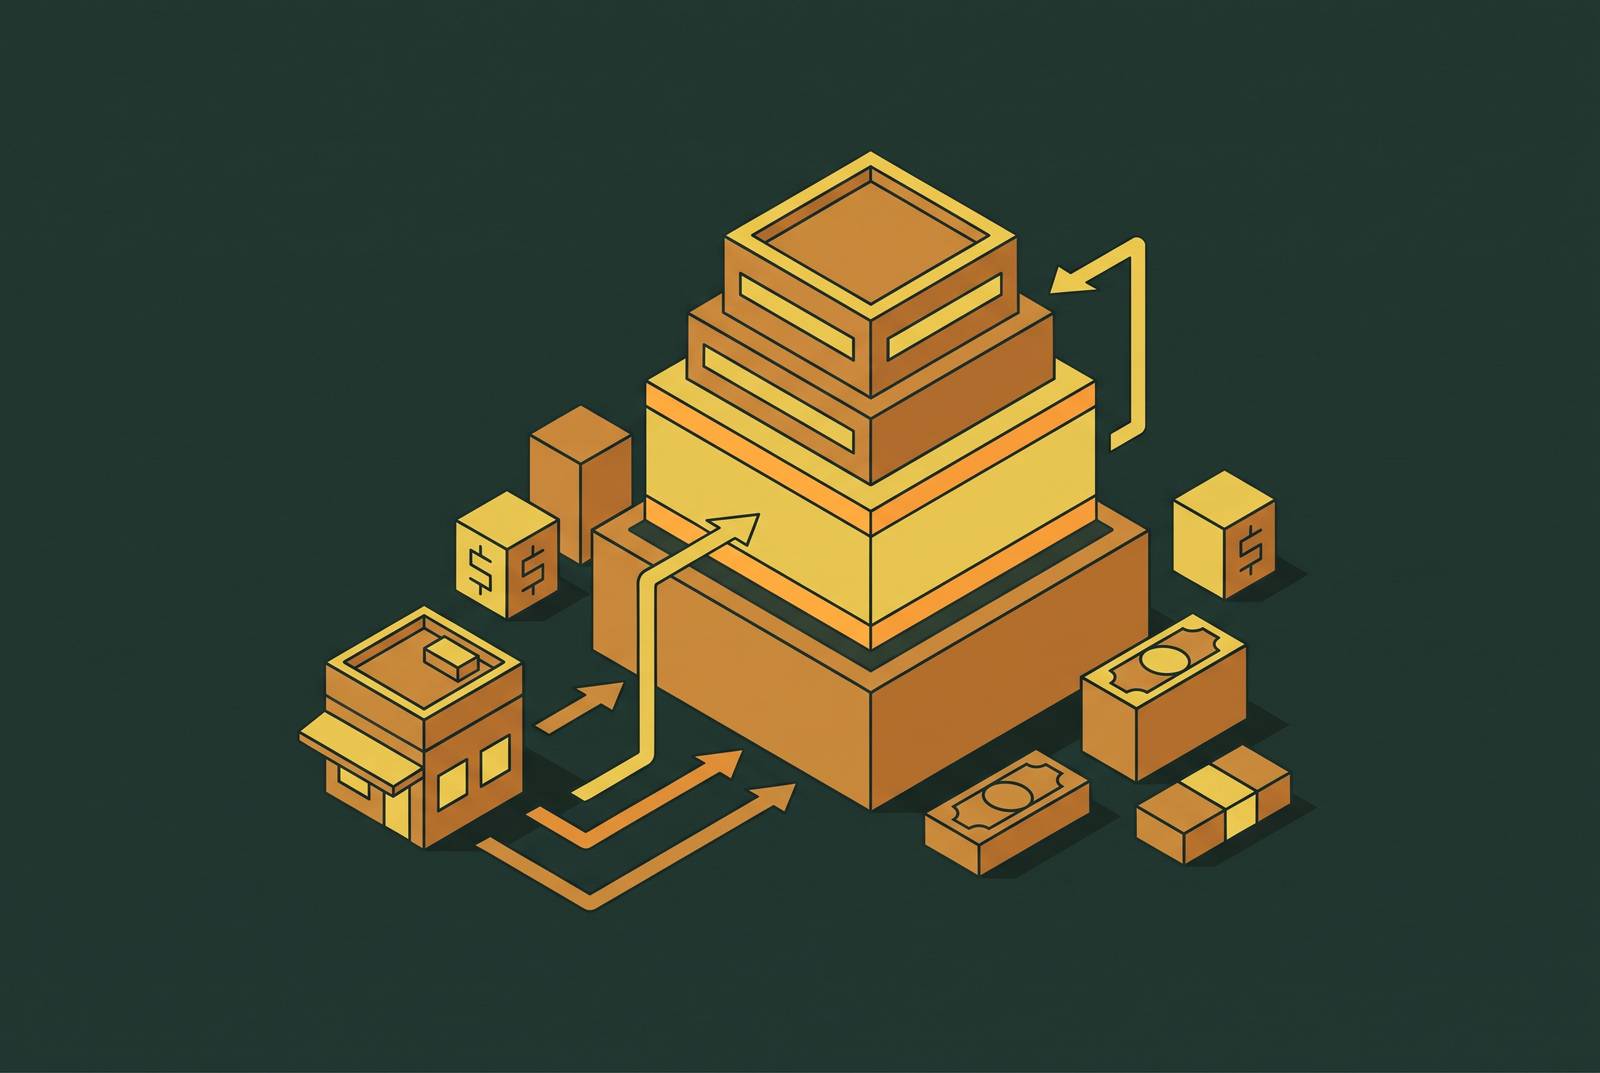
Picture the capital stack as a hierarchy of claims. Senior debt takes 50 to 70% of total capitalization, holds the first lien, costs the least, and gets paid first. Mezzanine debt takes another 10 to 20%, sitting above senior debt but below equity. Preferred equity fills 5 to 15% with a priority return but no lien. Common equity absorbs whatever's left, usually 20 to 40% of the stack, and it's the first money to lose value when a deal goes sideways. Cash moves up that stack when a property performs; losses move down it when a property doesn't. That single fact, more than any rate or covenant, is what "position" actually means.
Mezzanine sits in a precise spot: senior to the sponsor's own equity, subordinate to every dollar of third-party senior debt. That middle position defines its rights in a workout and its risk in a downturn at the same time. Most sponsors get one detail wrong here, and it's the detail that matters most. Mezzanine debt is secured by a pledge of the ownership interest in the entity that owns the property, not by a mortgage on the real estate itself. That single structural choice, a pledge of equity rather than a lien on dirt, shapes almost everything about how mezzanine behaves once a deal breaks.
Banks rarely originate this paper. The lenders writing mezzanine loans are private credit funds, real estate debt funds, life insurance companies, and, on smaller deals, high-net-worth individuals writing checks directly. Industry commentary notes that mastery of the capital stack is one of the clearest dividing lines between sponsors who make it through a down cycle and those who don't.
What makes mezzanine debt distinct from senior debt and equity
Mezzanine carries an interest rate, fixed or floating, the same as a bank loan does. That's where the resemblance ends.
Most mezzanine loans carry an equity kicker, warrants, conversion rights, or some other mechanism that hands the lender a small ownership stake if the deal performs well. That hybrid design, part loan and part option on upside, is why mezzanine costs more than senior debt and why lenders accept the subordinated position. The pricing logic across the stack makes the risk visible: senior debt runs 5 to 8%, mezzanine runs 10 to 15%, preferred equity targets an 8 to 12% preferred return, and common equity chases 15%-plus IRR. Each layer prices for exactly the risk sitting behind it, not for the risk sitting in front of it.
Current mezzanine pricing runs roughly 11 to 16%, with the exact number set by the LTV attachment point, the property type, and the sponsor's track record. That premium over senior debt reflects the subordinated claim, the illiquidity of the position, and the real cost of enforcing it if something goes wrong. It reflects the subordinated claim, the illiquidity of the position, and the real cost of enforcing it if something goes wrong.
Sponsors conflate mezzanine with preferred equity constantly, and that's a mistake that costs real money in a default. The two differ in legal structure, in what a lender can actually do when the deal stops paying, and, as later sections cover, in where each one is even permitted to appear. Treating them as interchangeable "gap capital" is how a sponsor ends up surprised by a UCC foreclosure notice when they expected a soft cure conversation instead.
How mezzanine debt amplifies equity returns, and magnifies risk
Run the math on a sizable multifamily deal. Senior debt covers 65% loan-to-value. Layering in a mezzanine tranche priced at 13% pushes total leverage to 80%. The levered equity IRR moves from 14.2% to 19.8%, while the blended cost of capital rises about 180 basis points. That's the entire trade in one underwriting line: real upside, real cost, and a structure that only holds together if the numbers behind it hold too.
Mezzanine earns its place under a specific set of conditions, and sponsors who skip past this checklist are the ones begging for a cure period eighteen months later. Senior lenders cap proceeds below what the business plan needs, leaving a real gap to fill. The sponsor wants to close that gap without bringing in another equity partner and diluting the deal further. Projected cash-on-cash and IRR, even after paying the mezz coupon, still clear the fund's hurdle rate with room to spare. And the property's NOI is stable or growing enough to carry the added debt service without strain.
It makes far less sense in the opposite conditions, and this is where excitement over "amplified returns" tends to blind sponsors to what happens on the way down. Thin or uncertain NOI turns a high mezzanine coupon into a cash-flow cliff the moment performance dips. A senior lender that prohibits subordinate debt outright, or an intercreditor negotiation that drags past the closing deadline, kills the structure no matter how attractive the returns look on a spreadsheet. A sponsor without the bandwidth to manage two lenders instead of one is taking on operational complexity it can't actually service, and that complexity becomes visible when the first covenant is missed.
Leverage cuts both ways here, and it cuts harder than most pro formas admit. The same structure that amplifies equity IRR on the way up erases equity value that much faster on the way down. The real execution risk never lives in the coupon. It lives in the document that governs how the two lenders deal with each other, and that document is where most of the actual negotiating happens.
How intercreditor agreements govern the mezzanine relationship
The intercreditor agreement decides how a senior lender and a mezzanine lender behave toward each other. It covers cure rights, standstill periods, purchase options, and consent requirements for any loan modification, and it determines how much a lender can recover and how fast a default gets resolved.
Deals get won or lost in the intercreditor negotiation. Sponsors walk into intercreditor negotiations assuming the structure is settled because the term sheets are signed, then find out the senior lender's counsel has redlined half the mezzanine lender's remedies. Once mezzanine debt enters a deal, senior lenders push for an intercreditor agreement stacked heavily in their favor: mezzanine cure rights get narrowed, senior consent gets required for basically any loan modification, and mezzanine's ability to act during a standstill period gets restricted almost to nothing.
Timing risk here is not theoretical. Senior lenders can take thirty to sixty days just to approve the intercreditor document, and if the two sides disagree over cure rights or standstill length, that timeline stretches further, sometimes past the sponsor's closing window. Build that risk into the deal calendar from day one, because waiting until the term sheet is signed to start the intercreditor conversation is how sponsors lose their rate lock.
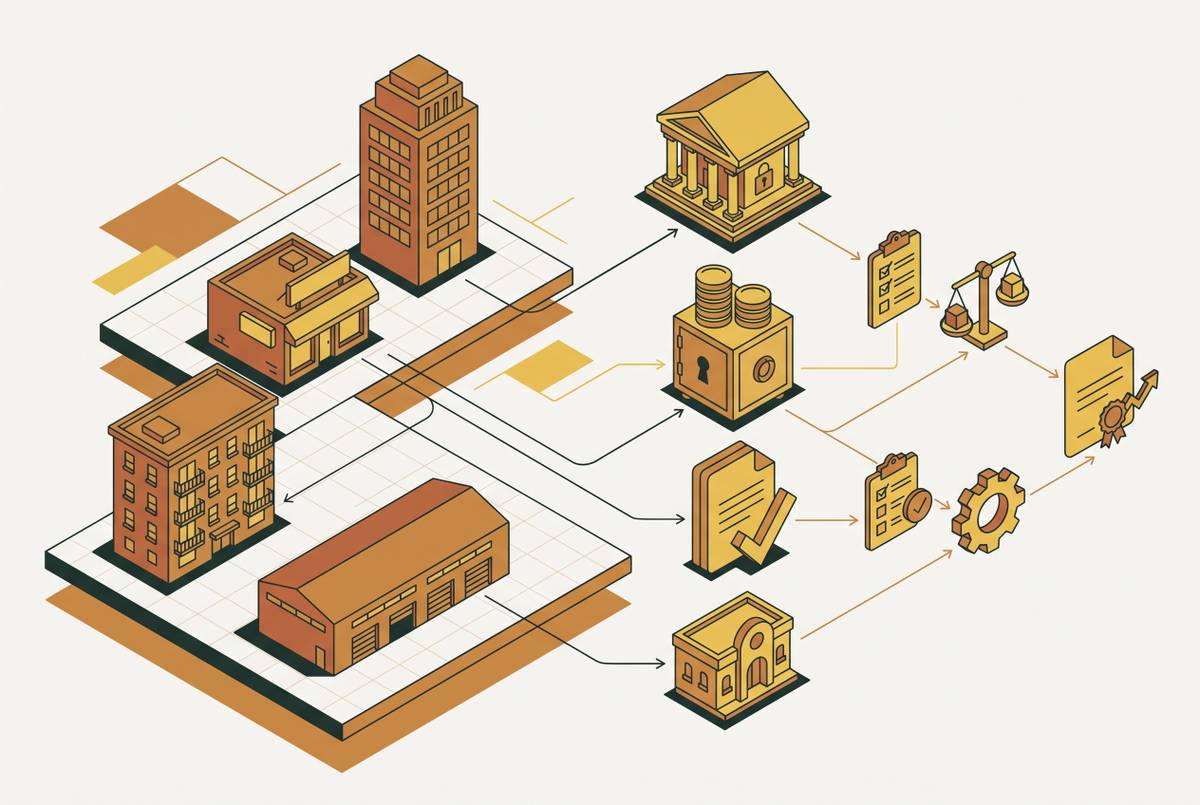
Real transactions show how granular these conditions get. In the BMO 2026-5C14 securitization, the Cummins Station loan permits mezzanine financing during the whole loan term, from an approved mezzanine lender, only if the combined LTV (whole loan plus mezzanine) stays at or below 65.0%, the actual combined DSCR doesn't drop below 1.35x, the actual combined debt yield stays at or above 9.5%, and the mezzanine loan is coterminous with the whole loan. None of that is boilerplate. Every one of those thresholds is a line a sponsor has to underwrite to before assuming mezzanine is even available.
Pricing is visible in the documents too. In the Barclays 2025 securitization, a mezzanine loan secured by the direct equity ownership in the borrower of the Shaner Philadelphia Airport Portfolio Mortgage Loan was originated on an interest-only basis, with pricing consistent with the mid-range of current mezzanine market rates. That single data point tells a sponsor roughly where hospitality-backed mezzanine was pricing at the time.
None of this argues against using mezzanine financing. It argues for bringing in real estate counsel early and building the intercreditor timeline into the deal from the start, not after the term sheet is signed.
UCC Article 9 foreclosure: what enforcement looks like for mezzanine lenders
A mezzanine lender never forecloses on the building. It forecloses on the equity interest in the entity that owns the building, and that difference changes everything about how fast and how final a default plays out.
The mechanism is a UCC Article 9 sale, a foreclosure on a security interest in personal property, the membership or partnership interest, not a real estate foreclosure under state property law. Three things separate it from a mortgage foreclosure. It moves fast, often completed in weeks rather than the months or years a judicial mortgage foreclosure can drag on for. It runs under the Uniform Commercial Code, a single statutory framework rather than the patchwork of state-by-state property law that governs mortgages. The process ends with the mezzanine lender owning 100% of the entity, and by extension, the property itself.
That speed and finality is why senior lenders comb through every line of the intercreditor agreement. A mezzanine lender that forecloses doesn't just step into a lien position. It becomes the new equity owner of the borrower entity and the senior lender's counterparty overnight. Senior lenders want to know, in granular detail, who that counterparty could turn out to be, long before it happens.
For sponsors, the contrast with a mortgage default is stark. A judicial foreclosure can drag on long enough to find a rescue capital solution. A UCC foreclosure offers no such runway: once a mezzanine lender decides to act, there's very little time to reorganize. That's why cure rights inside the intercreditor agreement matter so much, and why they get fought over so hard during negotiation. They're often the sponsor's only real protection.
Preferred equity looks nothing like this in a default. Preferred equity holders generally cannot trigger a UCC foreclosure. Their remedies run slower and land softer, contractual rather than absolute. Agency lenders will accept preferred equity in a capital stack where they'd flatly prohibit mezzanine.
Where preferred equity replaces mezzanine
Preferred equity has become the default subordinate capital tool on a lot of deals, and not because sponsors prefer it on the merits. It gets used because the senior lender leaves no other choice. Anyone calling it "cheaper mezzanine" hasn't looked closely at why it actually gets chosen.
The clearest example is agency debt. Fannie Mae and Freddie Mac restrict mezzanine debt pledges on agency-backed multifamily loans to approved sources under specific guidelines, and on any deal carrying agency financing, which covers a large share of the domestic multifamily market, mezzanine debt is simply off the table. Preferred equity doesn't involve a pledge of the ownership interest in the same legally restricted way, so it clears most agency intercreditor frameworks. That makes it the only real gap-fill tool available once a sponsor is working with Fannie or Freddie paper, full stop, no negotiation.
A recent transaction shows the scale institutional preferred equity can reach. On December 9, 2025, a wholly owned subsidiary of Realty Income Corporation entered into a perpetual preferred equity agreement, contributing $800 million in exchange for a preferred equity interest in CityCenter, carrying a preferred return subject to capped annual escalators beginning several years after closing. Preferred equity's return range, 8 to 12%, sits below mezzanine's 10 to 15% for a broadly similar position in the stack. That gap is the direct price of a weaker enforcement remedy, not a discount.
Choosing between the two comes down to a short set of questions, and the answer to the first one usually settles it. If agency debt is in the capital stack, preferred equity is the only option available. If the senior debt is CMBS or bank-originated with a workable intercreditor process, mezzanine is usually the sponsor's preference, since its enforcement position is cleaner and its pricing tighter. Whether senior lenders are competing hard for deals, or conditions are tight enough that mezzanine lenders won't touch the risk, decides which tool actually clears underwriting.
A third option is emerging alongside both. C-PACE financing hit a record $3.5 billion in originations in 2025 and is becoming a real alternative in hospitality and other eligible property types. It isn't a subordinate debt instrument in the mezzanine or preferred equity sense, and it doesn't require senior lender consent the way those two do, which makes it a separate gap-filling tool rather than a substitute for either.
Drivers of rising demand for mezzanine debt in the 2026 lending environment
The single biggest driver is the maturity wall. Roughly $875 billion in commercial and multifamily mortgages come due in 2026, representing a substantial share of all outstanding CRE debt. That's a concentrated wave of refinancings hitting the market at once, and most of it was never underwritten for the rate environment it's now landing in.
The deals under the most pressure are the ones closed between 2019 and 2023 on floating-rate bridge debt, priced on the assumption that an agency permanent loan would take them out at maturity on favorable terms. Those permanent takeouts now price at rates that often don't support the original capital structure at all, leaving a real hole between what the new senior loan will fund and what's owed on the maturing debt.
That gap is the recapitalization story of 2026. Higher rates and tighter underwriting mean a new senior loan covers a smaller share of value than it did a few years ago, so owners either write a check for the difference or find capital to bridge it. Many are turning to mezzanine or preferred equity precisely for that bridge, and the sponsors who waited to line up that capital are the ones now racing the clock against a hard maturity date.
Sourcing that capital isn't uniform across the lending market, either. The Federal Reserve's Senior Loan Officer Opinion Survey found large banks reporting net easing of standards on construction, nonfarm nonresidential, and multifamily loans, while regional and community banks reported net tightening on construction and multifamily lending over the same period. A sponsor can't assume the same bank that was flexible last cycle will be flexible this one, especially if it's a regional or community lender rather than a money-center bank.
The structures winning deals in 2026 tend to pair a bank-originated senior note with a private credit junior note or a mezzanine tranche layered on top, unlocking total leverage that neither lender could offer alone. Sponsors who understand how to build that stack, and who to bring it to, have a real edge over the ones still shopping a single lender for the whole loan. alternative debt sources made up 24% of total domestic lending volume in 2025, well above the 10-year average of 14%. Private and alternative capital has moved from the edges of the market into the mainstream of how deals actually get financed, and the maturity wall is what's forcing that shift into the open.
The institutional capital behind today's mezzanine market
The mezzanine finance market was valued at roughly $197.05 billion in 2024, and industry projections show growth to $212.58 billion in 2025 and on to $453.96 billion by 2035, a compound annual growth rate of 7.88%. The mezzanine market is a large and growing asset class with its own fund managers, its own institutional infrastructure, and its own return benchmarks. It's a large and growing asset class with its own fund managers, its own institutional infrastructure, and its own return benchmarks.
industry data shows fundraising for mezzanine strategies bounced back about 26% after an 80% decline in 2024. That swing says more about the lumpiness of a handful of large fund closings than about any structural shift in appetite. Volatile fundraising numbers year to year are normal in a market where a few multi-billion-dollar vehicles can skew the total by themselves.
The private credit managers behind this capital are large, and getting larger. As of the first quarter of 2026, Apollo Global Management held the largest total credit assets under management among its peers, with Blackstone, Ares Management, KKR Credit, Oaktree, Blue Owl Capital, HPS Investment Partners (now part of BlackRock), Sixth Street, Antares Capital, and Golub Capital following behind in descending order. Mezzanine real estate lending is one line item among many on balance sheets that size, and the check-writer across the table is rarely a specialist boutique anymore.
since 2020, nonbank lenders have raised capital through a large number of closed-end debt funds targeting debt strategies. That buildout of private credit capacity is what's now getting drawn on as the 2026 maturity wall forces owners to look past their traditional bank relationships. Preqin data cited by GowerCrowd shows that private equity real estate assets under management surpassed $1.6 trillion in 2025, and that's the size of the capital pool circling every mezzanine structure, every intercreditor negotiation, and every recapitalization described here.
For a sponsor sitting across the table from a mezzanine lender in 2026, that lender is far more likely to be a multi-billion-dollar credit fund with a dedicated real estate debt team than a bank branch loan officer. Knowing that counterparty landscape, who's writing these checks, at what size, and under what conditions, isn't optional knowledge anymore for anyone trying to close a deal in this market. Lev, a commercial real estate AI and data platform that gives sponsors and brokers access to real-time lender data alongside purpose-built deal tools, is one resource built around exactly that kind of capital stack intelligence.