Senior, Bridge, and Mezzanine Loan Structures in CRE
Each layer of CRE debt solves a different problem at a different stage of a deal's life.
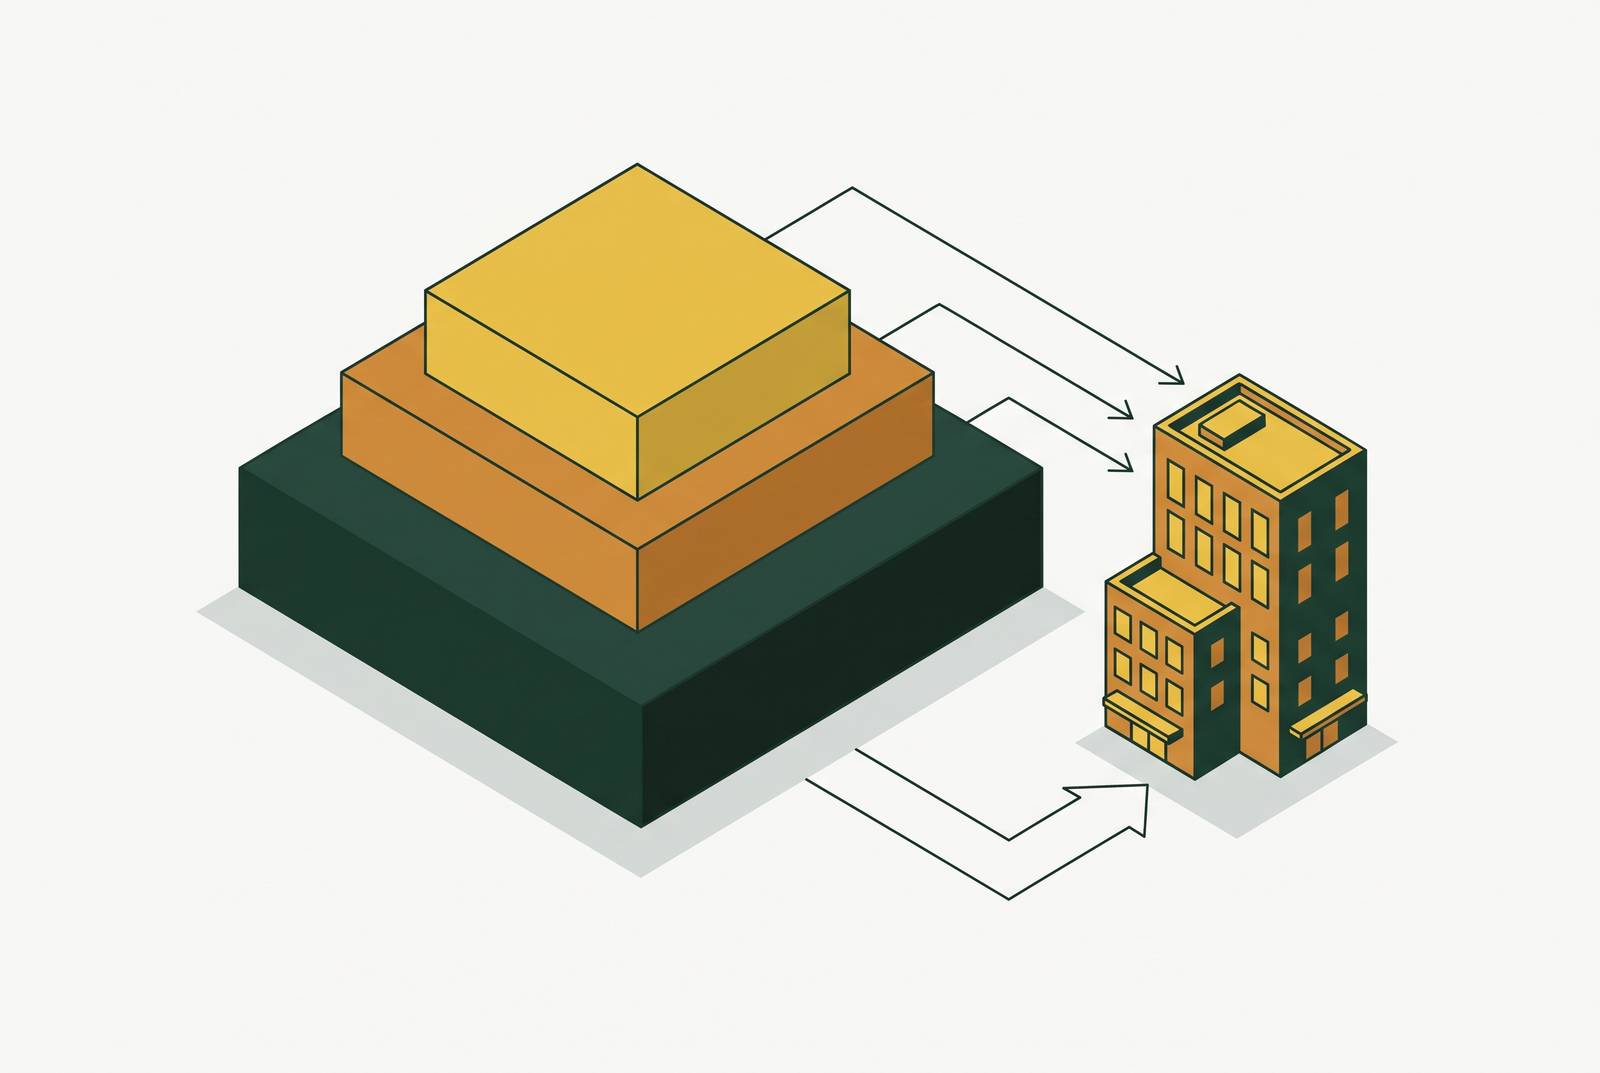
A commercial real estate deal rarely gets funded from one source at one price. The capital stack exists precisely because no single lender wants to carry the whole risk of a project, and no single loan structure fits every stage of a deal's life. Sponsors who pick the wrong layer, senior debt for a transitional asset, bridge financing stretched out as if it were permanent debt, mezzanine piled on top of a deal that never needed it, pay for that mistake in real dollars, not theoretical ones.
The capital stack is just financing arranged by who gets paid first. If the deal goes sideways, whoever sits at the top of the stack gets repaid before anyone below them sees a dollar, and that repayment priority sets the price of every layer beneath it, because each layer's risk, and therefore its cost, is determined by its position in that repayment order. Several layers generally make up a stack: senior debt, bridge loans, mezzanine financing, and preferred equity, among others. Each one solves a different problem at a different point in a deal's life, and none of them substitute for each other cleanly. Understanding where each layer belongs, and what it costs when a sponsor forces the wrong one into a deal, is close to a prerequisite for working in this business at all. Bridge loans used as long-term financing, for instance, routinely cost sponsors an extra 2 to 4 percentage points a year in cost of capital, according to Avana Capital's guide, simply because the loan was never designed to sit on a balance sheet past stabilization. Platforms like Lev, a CRE-specific AI and data platform where sponsors and brokers run deals with real-time market intelligence and purpose-built deal tools, are built in part around making these stack decisions legible before a term sheet is ever requested.
How senior debt works and what deals it fits
Senior debt holds the first claim on the property. It's secured through a mortgage or deed of trust, and if the borrower defaults, the senior lender gets repaid before any mezzanine holder, preferred equity investor, or common equity partner sees a dime. That priority is the entire reason senior debt is the cheapest money in the stack: lenders accept a lower yield because their downside is structurally protected.
Who writes these loans depends on the asset and the borrower. Banks, life insurance companies, agency lenders active in multifamily, CMBS conduits, and credit unions all originate senior debt, and each comes with its own underwriting culture and closing timeline. What they're all checking, in one form or another, is debt service coverage ratio, loan-to-value, debt yield, occupancy trends, and sponsor strength, according to Blooma's guide. Those five inputs decide how much a lender will advance and at what rate.
Senior debt fits stabilized, income-producing property with a track record. A multifamily building running at high occupancy with two years of clean financials is the textbook case. Senior debt does not fit anything transitional: a property mid-renovation, a building still filling up after construction, or a value-add deal where cash flow hasn't found its floor yet, all fail to qualify. None of those can clear DSCR minimums or LTV ceilings at the senior level, because the income a senior lender needs to underwrite simply isn't there yet.
Pricing varies by lender type. Per YieldStack's comparison, bank loans run roughly 6.5% to 8.5%, agency debt runs 5.5% to 7%, and CMBS runs 6% to 8%; asset class, term, and recourse status drive the spread inside each range. Most senior lenders cap leverage at 65% to 75% loan-to-value, and that ceiling is the whole problem this piece exists to solve. Whatever percentage of the purchase price or project cost sits above that line has to come from somewhere, and it's either equity, or it's one of the two structures covered next.
What bridge loans are designed to do
Bridge loans exist for one job: short-to-medium-term financing for a property that either can't qualify for permanent debt yet, or needs capital faster than a permanent lender can close, according to Avana Capital's guide. It's financing built around a gap in time, not a gap in the capital stack's vertical structure the way mezzanine is.
Five situations drive most of the volume. Acquisition speed is the most obvious: a bridge loan closes in 30 to 60 days versus 60 to 120 for permanent debt, which matters enormously when a seller has three offers on the table and a 45-day close requirement. Value-add deals need bridge because the property needs renovation or lease-up before it can meet permanent underwriting. Stabilization plays need it because even a fully leased property sometimes needs a season or two of clean financials before a permanent lender will touch it. Recapitalization uses bridge to pull cash out, restructure existing debt, or buy out a partner. And distressed situations, properties facing loan maturity with no permanent refinance available, use bridge as rescue capital, which is the highest-risk, highest-cost end of the category.
Structurally, bridge looks nothing like a 10-year fixed-rate mortgage. Terms run 12 to 24 months, sometimes stretching to 36 with extension options. Rates float, typically SOFR plus 350 to 600 basis points, landing in the 8% to 11% all-in range per Avana Capital. Payments are interest-only, with no amortization eating into principal during the term, and personal guaranties from sponsors are standard rather than exceptional. Underwriting depends primarily on the property's value, the credibility of the business plan, and the realism of the exit refinance, and these factors drive loan approval more than the sponsor's balance sheet, though the sponsor's financials still get checked.
That exit is not a footnote, it's the load-bearing assumption of the entire loan. Every bridge loan needs a planned path out, almost always a refinance into permanent debt once the property stabilizes. A bridge loan modeled without a credible exit is a problem pushed 18 months down the road with interest accruing on it. It's a problem pushed 18 months down the road with interest accruing on it.
Pricing splits by lender type too. Institutional bridge lenders are at the lower end of that 8% to 11% band but move slower and underwrite deeper. Private debt funds sit higher on rate but close faster and tolerate more deal complexity. Hard money lenders run 9% to 14% or higher, fixed or floating, underwrite almost purely on the asset, close the fastest, and cap leverage lowest, typically 65% to 70% LTV. Bridge financing appears most often in multifamily, hospitality, office repositioning, and industrial deals, wherever a sponsor has a business plan that can plausibly get the asset to stabilization inside the loan term.
How mezzanine financing fills the gap senior debt leaves
Mezzanine debt sits between the senior mortgage and the sponsor's own equity, and it exists specifically because senior lenders stop at 65% to 75% LTV and most sponsors don't want to, or can't, fund the rest entirely out of pocket. The name comes from architecture: a mezzanine floor sits between the ground level and the main floor above it, and mezzanine debt occupies that same in-between position in the stack, as Bridge.co's 2026 explanation puts it.
The security mechanism is where mezzanine gets interesting, and where it diverges completely from a second mortgage. Rather than a lien on the property itself, the mezzanine lender takes a pledge of the ownership interests in the entity that owns the property. That distinction isn't cosmetic. It means that on default, the mezzanine lender can step in and take control of the ownership entity directly, without running the borrower through a standard foreclosure process, which changes the entire enforcement calculus and, by extension, the negotiation that happens between senior and mezzanine lenders before the deal ever closes.
The rate on mezzanine debt looks alarming next to senior debt until it's benchmarked against the right comparison. Hotel mezzanine typically runs 12% to 20%, depending on property quality, sponsorship strength, LTV, and whether cash flow is stabilized or still transitional, per Bridge Marketplace's guide. Set against a 6% to 7% senior loan, that looks expensive. Set against equity, it looks like a bargain: an equity partner targeting a high internal rate of return keeps permanent ownership of the deal, while a mezzanine lender at 15% gets repaid on a schedule and exits. Bridge.co's illustrative stack, senior debt at 65%, mezzanine at 20%, equity at 15%, shows the blended cost of the debt portion coming in well below what it would cost to fund that same 20% entirely with equity. The principle holds that mezzanine debt is best used to thin out the equity layer, not replace it.
Most mezzanine deals carry an equity kicker too, warrants or conversion rights giving the lender a small ownership stake if the deal performs well, according to Bridge.co. CAIA's analysis, also cited by Bridge.co, puts the total return mezzanine investors target in the 12% to 17% range overall, with the coupon covering most of that and the equity kicker making up the rest, alongside anti-dilution provisions protecting that stake.
Real filings back this up with numbers that would otherwise sound theoretical. In the BMO 2026-5C16 Mortgage Trust, one mezzanine loan carries monthly interest-only payments at 11.000% per annum, running coterminous with the underlying mortgage. The Crossgates Mall whole loan inside that same trust stacks eight senior pari passu notes at 8.5%, a subordinate note at 14.0%, and a separately originated mezzanine loan with a $20.0 million original principal balance accruing at 20.0000%. Those numbers, straight from SEC filings, show the full 11% to 20% range isn't a hypothetical spread analysts model, it's actively priced into live deals.
Hotels lean on mezzanine especially hard: acquisition gap-filling where senior lenders cap out at 60% to 65% LTV, PIP funding when a brand mandates a renovation program, repositioning where a major renovation temporarily kills cash flow, and construction budget overruns where the senior loan comes up short. Preferred equity looks similar on a stack diagram but isn't the same instrument. Mezzanine is debt with enforcement rights attached; preferred equity is, legally, an equity investment with priority distributions. That distinction drives different tax treatment, different intercreditor terms, and a different set of remedies if the deal defaults.
The intercreditor agreement and why it shapes every layered deal
An intercreditor agreement is the contract between the senior lender and the mezzanine lender that spells out exactly who can do what, and when, if the deal goes into default. Any stack that combines a senior mortgage with mezzanine debt needs one. It is the mechanism that keeps two lenders with competing interests from tripping over each other the moment a borrower misses a payment.
The ICA governs what the mezzanine lender can actually do on default: how fast they can act, whether they have to cure the senior loan first, and how much room the senior lender has to block them. Deals aren't getting simpler on this front. Intercreditor negotiations between senior and mezzanine lenders are getting more involved, not less, in 2026, driven by rising deal complexity and lenders getting choosier about who they'll share a capital stack with.
The Benchmark 2026-B42 CMBS prospectus, per its SEC filing, requires a combined maximum LTV test, a combined minimum DSCR test, a combined minimum debt yield test, and a required intercreditor agreement as conditions for permitting mezzanine debt behind a senior loan, all laid out in the deal's Annex A mezzanine permissions table. That deal's Annex A mezzanine permissions table is not boilerplate. The Annex A mezzanine permissions table is the actual gatekeeping mechanism that permits or blocks a mezzanine tranche.
Sponsors and brokers need three questions answered before a layered deal closes, not after. Does the mezzanine lender have cure rights on a senior default, and how many days do they get? Can the mezzanine position be sold to a third party without the senior lender's consent? And can the mezzanine lender act on its ownership pledge while the senior lender is still working through its own remedies, or does a standstill provision freeze them out? Sponsors bringing a two-layer stack into a deal should expect ICA negotiation to add real time and real legal cost to closing, and underestimating that timeline is one of the most common, and most avoidable, causes of a delayed close.
One structural pattern is emerging from all this complexity: stack C-PACE financing ahead of senior debt on energy-efficient projects, then use mezzanine only for whatever gap remains, and a bank senior paired with private credit mezzanine now often beats an all-bank structure outright, because the bank's senior loan sizes larger when a credible subordinate lender is standing behind it, according to a source on commercial development financing strategies.
The 2026 lending environment and what it means for how sponsors choose their structure
Credit is loosening in 2026, and the numbers back that up unambiguously. One industry trade group forecasted total commercial mortgage origination volume of $805.5 billion for the year, up from $633.7 billion expected in 2025, a jump that reflects real acceleration, not a rounding error. Commercial lending momentum in the first quarter of 2026 saw origination volume, average loan size, and non-agency lending all climbing at once.
Banks alone originated $455 billion in CRE loans in that first quarter, an 80% jump from Q1 2025, while private market lending surged 133% over the same stretch, pushing overall commercial and multifamily borrowing up 52% year over year. One brokerage's 2Q26 domestic Capital Markets Conditions & Trends report found debt origination up 25% year to date to $453 billion through the first half of the year, with debt fund originations growing fastest at 54%, ahead of bank originations at 45%.
None of this means the market has gone frothy. Banks, life insurance companies, CMBS lenders, debt funds, and the CLO market are all active in 2026, but underwriting discipline hasn't disappeared alongside the volume increase. Private credit has quietly become a permanent fixture of the capital stack rather than a stopgap: alternative debt sources made up 24% of domestic lending volume in 2025, well above the 10-year average of 14%, per Northspyre and Deloitte. That shift matters structurally, because Basel III endgame rules push banks toward higher risk weights on certain CRE exposures, and banks respond by pricing wider, shrinking commitments, or pushing exposure off balance sheet entirely, one of the reasons the bank-senior-plus-private-credit-mezzanine combination keeps gaining ground.
Not every asset class is riding this wave equally. Office delinquencies remained elevated among major CRE categories heading into 2026, and lenders broadly remain cautious on office exposure. Hotels are a different story: hotel mezzanine financing stays critical in 2026, particularly with $76.6 billion in CMBS loans maturing and forcing owners to rework their capital stacks, according to Bridge Marketplace's guide. And across the board, senior loan commitments are running smaller relative to total project cost compared to recent peak years, which widens the gap that mezzanine or preferred equity has to close. Sponsors modeling a deal in 2026 should build the full stack from day one rather than treating the subordinate layer as an afterthought bolted on after the senior term sheet comes back. Banks, for their part, increasingly want to see a clear take-out or mini-perm structure built into the deal before they'll commit at all, which puts the burden back on sponsors to know, before they ever pick up the phone, exactly which layer of the stack they're actually asking for.
Sources
- Commercial Bridge Loans: The Complete 2026 Borrower's Guide | Avana Capital
- Mezzanine Financing Explained 2026 | Rates and Capital Stack
- 7 Types of Commercial Real Estate Loans Compared
- bridgemarketplace.com
- hbcapitalre.com
- Commercial Development Financing Strategies 2026
- aaplonline.com
- commercialrealestate.loans