Why Commercial Loan Underwriting Takes so Long
Complex commercial assets require deeper scrutiny than residential loans demand.
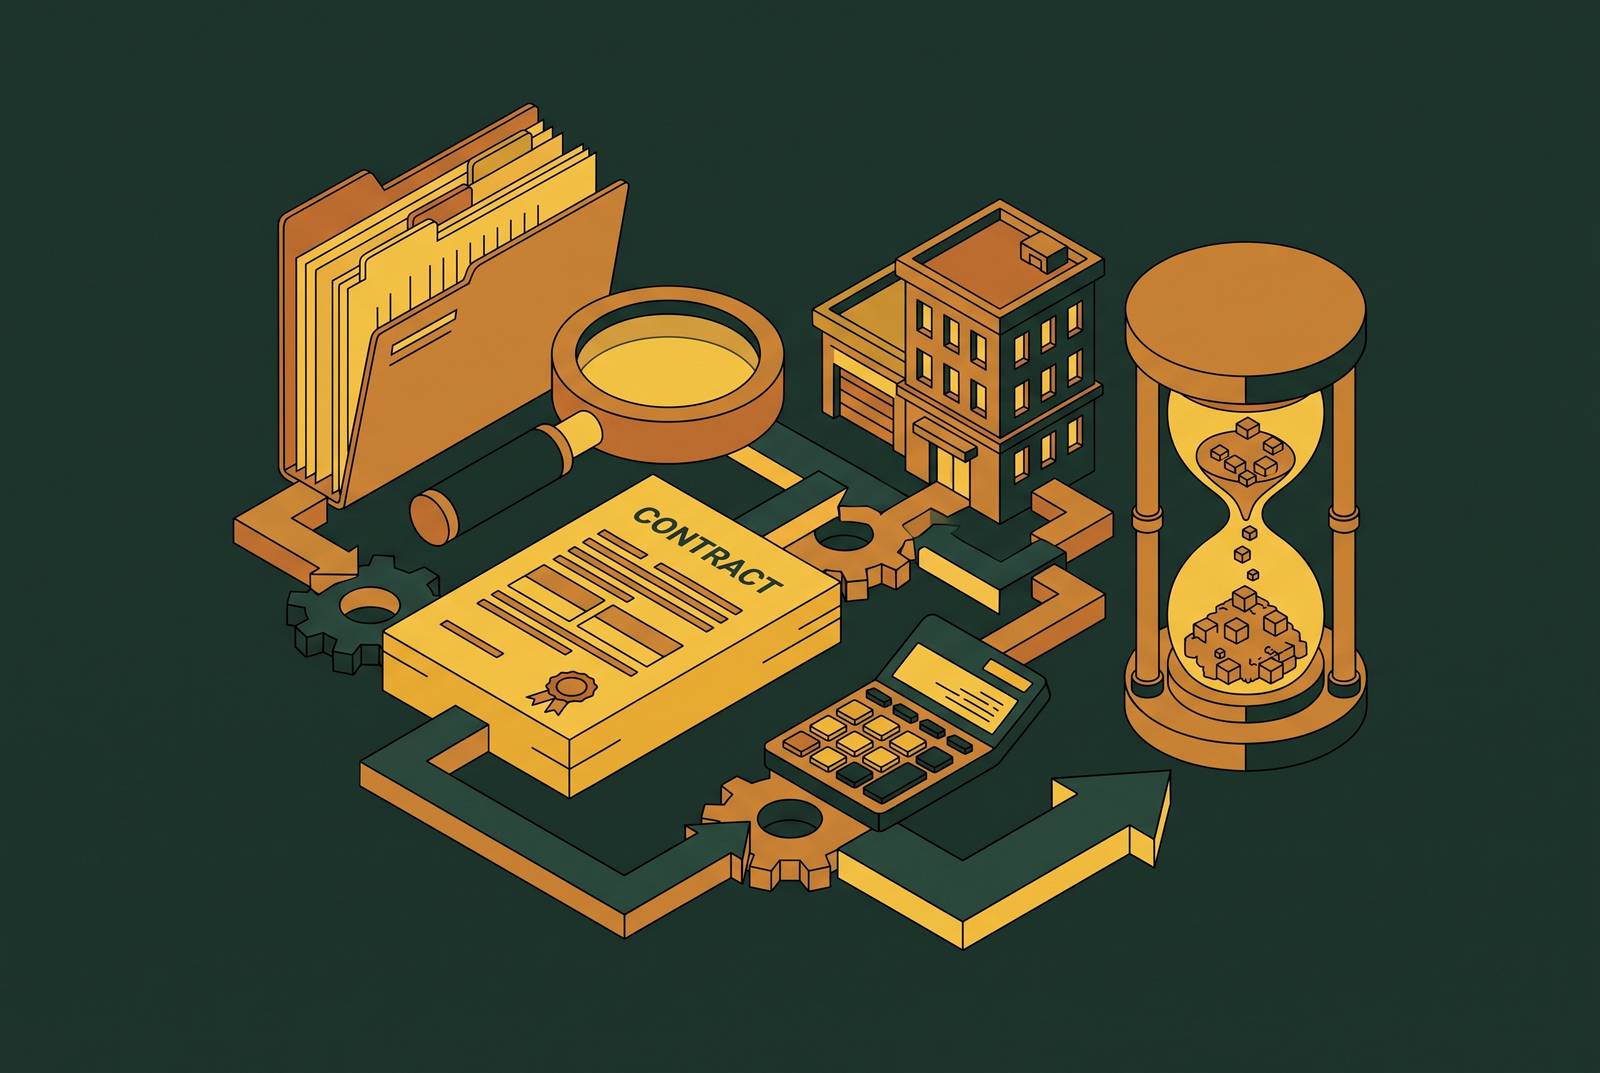
A residential mortgage can clear underwriting in a matter of days once the file is complete. Commercial loan underwriting rarely moves that fast, and the reason has little to do with lenders dragging their feet. Residential and commercial underwriting evaluate different things entirely at different speeds. A residential underwriter is looking at a borrower's personal income, credit, and debt load. A commercial underwriter is looking at a property's ability to generate income, the strength of its tenants, its position in the local market, and its physical condition, on top of the borrower's own financial standing. That is a wider and messier set of questions, and the timeline reflects it. A simple deal with a strong borrower and a stabilized, single-tenant asset can close in a few weeks. A mixed-use development with layered ownership and uneven cash flow often takes 60 to 90 days or more. That gap between a few weeks and three months isn't inconsistency on the lender's part. It tracks the complexity of the deal itself, and the rest of this piece works through why each stage of that process takes the time it does.
Appraisal and third-party reports
The single biggest piece of a commercial underwriting timeline usually isn't anything the lender controls directly: the appraisal, and often the environmental review that comes with it. A commercial appraisal involves an income analysis, a set of comparable sales, and sometimes a cost approach on top of that, which puts it in a different league from a residential appraisal in both scope and turnaround. When a Phase I environmental assessment turns up a recognized environmental condition, such as a former dry cleaner, a gas station, or a site with a history of industrial chemical storage, a Phase II assessment follows, and that can add several more weeks before the file is ready to move forward. None of this sits inside the lender's control. The lender doesn't write the appraisal, can't push the appraiser to work faster beyond ordinary scheduling, and underwriting can begin before the appraisal is in hand but can't be completed without it, since the appraised value sets the loan-to-value ratio that drives loan sizing. That's a hard dependency on an outside party, and no amount of internal process improvement on the lender's side removes it. Lenders that order title work and surveys early can run some of these third-party reports in parallel rather than waiting on each one in sequence, which helps, but the appraisal itself still has to land before underwriting can close out. The one lever that sits with the borrower is timing: ordering the appraisal as soon as initial terms are in hand, rather than waiting for the formal application to be submitted, is one of the few moves on the borrower's side that meaningfully shortens how long the whole process takes.
Why documentation collection stalls deals before underwriting even begins
Before any of that third-party work finishes, a separate clock is already running, and it has nothing to do with appraisers or environmental consultants. Incomplete documentation is the most common cause of delay in commercial underwriting, responsible for roughly 60% of the holdups lenders see, and having financials, leases, and entity documents ready at the time of application can save one to two weeks on its own. A full commercial loan package is a long list: personal financial statements and tax returns, business financial statements, rent rolls and lease copies, trailing twelve-month operating statements, purchase or refinance documentation, entity documents, and in many cases environmental reports. Pulling all of that together from accountants, property managers, attorneys, and the borrower's own files takes real time, even when everyone involved is cooperating fully. The process is sequential rather than forgiving: a lender waiting a week on a rent roll loses that week from the total timeline, full stop, because nothing downstream can start until the document arrives. Part of what makes this slow isn't anything to do with borrower effort. Rent rolls show up as spreadsheets, PDFs, or exports from whatever property management software the owner happens to use. Operating statements follow whatever template the borrower's bookkeeper built years ago. Leases arrive as scanned images of wildly varying quality. Someone on the lender's side has to collect, organize, and check all of this material for completeness before any underwriter can start analyzing a deal, and that step rarely appears in the timelines borrowers are given, even though it eats real days off the calendar.
Underwriting analysis after document collection
Once a complete file reaches an underwriter, the work that follows is not a matter of checking boxes. Underwriters evaluate the debt service coverage ratio, which typically has to clear 1.20 to 1.25x, the loan-to-value ratio, which is usually capped well below the full value of the property, the borrower's credit history and track record, and the condition of the property alongside the fundamentals of its local market. Each of those metrics draws on a different document or set of documents, and none of them can be taken at face value. Income gets normalized against realistic assumptions. Market vacancy rates get applied rather than whatever occupancy figure the seller's broker quoted. Expense growth gets stress-tested against inflation and maintenance history. Income streams that aren't contractually guaranteed get discounted below full value. Lenders also run the deal forward in time: approval depends not just on how the numbers look today but on how they'd hold up under a higher refinance rate at maturity, a lower exit cap rate, or a drop in net operating income, which is a meaningfully different exercise than reading a current balance sheet. On the borrower side, the underwriter is working through debt-to-income ratio, loan-to-value, collateral, time in business, cash flow stability, and bank account history, and in a commercial file, most of these require cross-referencing several documents. A deal structured through a partnership, an LLC with multiple members, or a property held in trust adds another layer of review, since entity documents and guarantor financials each need their own verification. A past bankruptcy or delinquency doesn't get waved through on the strength of a credit score. It requires a documented explanation and additional scrutiny from the underwriter before the file can move forward. None of this reflects underwriters working slowly. It reflects a process built to verify every input against its source before the lender puts capital behind it.
Manual financial spreading inside the lender's own walls
One particular step inside that process deserves its own attention, because it consumes more analyst time than almost anything else, and borrowers rarely hear about it. Financial spreading is the work of pulling figures out of borrower documents and entering them into the lender's own models and templates, and most of that work still happens by hand. An analyst pulls numbers from trailing twelve-month operating statements, rent rolls, offering memoranda, appraisals, and tax returns, then types and organizes that data into internal templates and credit models line by line. Every point where the data changes hands, from the original document to the analyst's working file, from one analyst to a senior reviewer, from the credit model to the approval memo, is a point where something can slip: a delay, a typo, a figure that no longer matches what the borrower actually submitted. The same format problem that slows down document collection occurs again here in a different form. Rent rolls use different column layouts depending on who produced them. Operating statements label the same line item differently depending on whose template was used. Lease abstracts read differently depending on which attorney drafted the lease. None of this fits a standard template without a person sitting down and making judgment calls about how to map one format onto another. When analysts spend most of their working hours moving data from one place to another rather than evaluating the assumptions behind it, the whole operation runs into a capacity limit. How many deals a lender can move through its pipeline in a given month is set by how many hours its analysts have for spreading, not by how much capital is available or how good the deals in the pipeline are.
How delays cascade across stages
All of this connects into a single structural fact about how commercial underwriting is built: the stages run in sequence, not in parallel, and a delay in one doesn't stay contained to that one stage. The standard five-phase structure, pre-qualification, document collection, appraisal and due diligence, underwriting analysis, and approval and closing, isn't a set of independent lanes a lender can freely reorder to save time. Each phase gates the one after it. Underwriting can't close out until the appraisal is finished, because the appraised value sets the loan-to-value ratio, which in turn sets how large the loan can be. The appraisal can't be ordered until the lender has accepted the application. The application can't go in until the borrower's documents are assembled. A two-week delay in getting the appraisal back doesn't just cost two weeks. It costs two weeks plus whatever has to be rescheduled downstream: the underwriter's calendar block that now sits empty, the closing attorney who was booked for a date that no longer works, the rate lock that was priced against a closing date that has now moved. Title problems, a lien nobody flagged earlier, an easement dispute, a boundary question, discovered late in the process can force a lender to reopen a stage that looked finished weeks earlier. The practical upshot of all this is that preparation early in the process carries outsized weight. A document delivered in week one that would otherwise have shown up in week three doesn't just save two weeks on its own. It prevents the entire chain of rescheduling and recalendaring that a two-week gap would otherwise set off downstream.
The maturity wall and the structural cost of slow underwriting
The stakes of all this extend well past any single deal, because of how much commercial debt is coming due at once. A large volume of commercial real estate loans is reaching maturity across several consecutive years in the current cycle, and that volume is generating refinancing demand that manual underwriting workflows were never built to absorb at this scale. No deal moving through a slow underwriting process is really competing on its own. It's competing with every other deal in the market for the same limited pool of appraisers, the same underwriter capacity, and the same closing attorneys. For a borrower with a loan maturing on a fixed date, a delay in underwriting isn't just an inconvenience. It can mean a forced extension, penalty interest, or in the worst case a forced sale of the asset if refinancing doesn't close in time. For lenders, a pipeline capped by manual processes translates directly into fewer deals closed per analyst each quarter, which limits revenue right when deal volume in the market is at its highest. Firms that can underwrite faster, through better preparation, cleaner data, and better tools, don't just close individual deals sooner. They get invited to more deals in the first place, and they set the terms of negotiation more often than firms stuck waiting on their own internal process.
What technology can and cannot do about these bottlenecks
Better tools actually help with some parts of this process and not others. The appraisal and the Phase I environmental assessment can't be automated out of the process. They're third-party expert opinions required by lender policy and, in many cases, by regulation, and the correct response to their timelines is ordering them earlier and preparing for them better, not trying to eliminate them. Document collection and normalization, financial spreading, populating the initial underwriting model, and drafting the credit memo form a different category of work. These are the stages where most of an analyst's time goes into handling data rather than exercising judgment, and they're the stages where AI-native tools built specifically for commercial real estate documents can turn a multi-day task into a matter of hours. The distinction between a general-purpose document tool and a platform built for this kind of document matters here, because rent rolls, trailing twelve-month operating statements, offering memoranda, and agency workbooks don't follow a standard format the way a routine personal financial document does. A tool built to read these documents natively produces more reliable extraction than general-purpose optical character recognition adapted after the fact to handle them. For regulated lenders, speed by itself isn't the goal. Underwriting output has to be auditable, with a clear line from the original borrower document through to the figure sitting in the credit model, and a workflow that automates extraction while keeping a human reviewer at each decision point delivers that speed without turning the process into something nobody can trace. Sponsors and brokers who build this kind of tooling into their process gain something that compounds over time: the capacity to screen more deals, produce cleaner packages faster, and respond to a lender's document requests without the usual lag changes how many deals a team of a given size can realistically take on.